
Choosing Between Professional Financial Advisors: A Strategic 2026 Guide
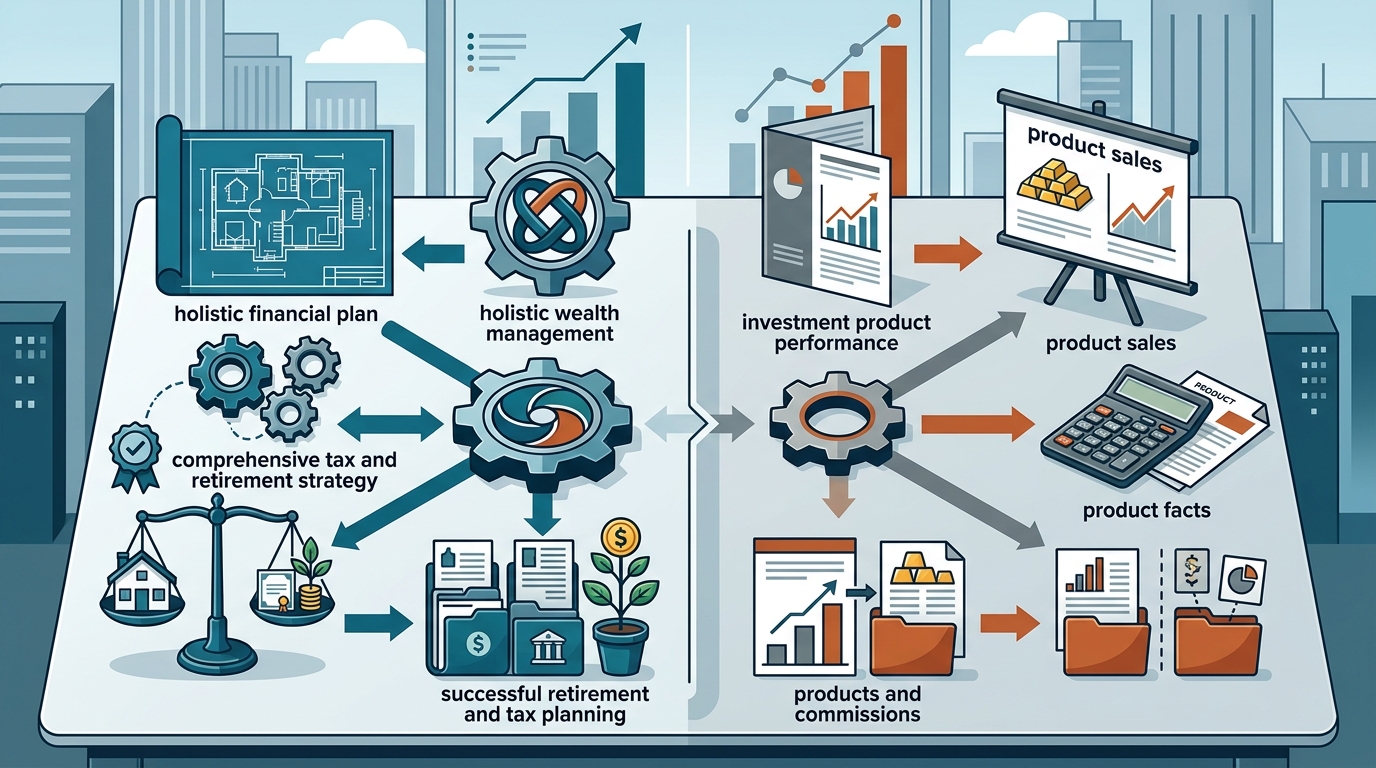
The financial landscape in 2026 has shifted dramatically from simple product sales to holistic wealth management. According to a 2025 industry report by the Certified Financial Planner Board of Standards, over 60% of Americans now seek professional guidance for complex tax and retirement strategies. This surge in demand has created a critical decision point for individuals: should you hire a traditional financial advisor or engage a specialized fiduciary consultant? The choice impacts not just your immediate portfolio performance but your long-term financial security. Understanding the structural differences between these professional paths is essential for making an informed decision that aligns with your specific net worth and goals.
Understanding the Fiduciary Standard
The most fundamental difference between professional financial advisors lies in their legal obligations to you. A fiduciary is legally bound to act in your best interest at all times. This standard eliminates conflicts of interest that might arise from product commissions. In contrast, non-fiduciary advisors, often referred to as brokers or insurance agents, are held to a suitability standard. This means they only need to recommend products that are suitable for your profile, even if those products generate higher commissions for them.
Fiduciary duty is not just a legal term; it is a core operational philosophy. At FP Financial, we adhere strictly to this principle. Our advisors are certified to provide unbiased advice on tax optimization, estate planning, and investment management. This distinction is crucial for high-net-worth individuals who require precise, conflict-free strategies. The fiduciary standard ensures that your wealth preservation is prioritized over product sales volume.
Analyzing Fee Structures and Costs
Cost transparency is a major differentiator in the advisory industry. Traditional advisors often operate on a commission-based model, where they earn a percentage of the financial products they sell. This can create an inherent bias toward more complex or expensive products. Conversely, fee-only advisors charge a flat fee, an hourly rate, or a percentage of assets under management (AUM). This structure aligns their success with your portfolio growth.
According to data from the Investment Company Institute, fee-based advisory accounts have grown significantly, reflecting a client preference for transparency. When evaluating costs, look beyond the headline number. Consider the value provided by tax-loss harvesting, estate planning integration, and behavioral coaching. These services often justify higher fees by preventing costly financial mistakes. For a detailed breakdown of our pricing models, visit our services page.
Depth of Service and Specialization
Not all financial advice is created equal. Generalist advisors may offer broad coverage but lack depth in specialized areas like cryptocurrency regulation, international tax law, or business succession planning. Specialized fiduciaries often possess advanced certifications such as the Chartered Financial Analyst (CFA) or Certified Public Accountant (CPA) credentials.
FP Financial specializes in comprehensive wealth management for professionals and business owners. Our approach integrates financial planning with real estate investment strategies and corporate tax planning. This holistic view is essential for clients who view their finances as a complex ecosystem rather than isolated accounts. The CFP Board of Standards outlines the rigorous education and experience required for these credentials. Choosing a specialist ensures that your unique financial challenges are addressed by experts in those specific domains.
Accessibility and Minimum Requirements
One common barrier to professional advice is the perception that it is only for the ultra-wealthy. Traditional brokerages often have high minimum investment requirements, sometimes exceeding $100,000 or $250,000 to open an account. This excludes many middle-income individuals who could benefit from professional guidance.
Modern fiduciary firms have democratized access to high-quality advice. Many now offer tiered service levels, including hourly consulting for specific questions or flat-fee planning for comprehensive roadmaps. This flexibility allows individuals at various stages of wealth accumulation to access professional support. According to a 2024 survey by the National Association of Personal Financial Advisors, the average client seeking holistic planning has a net worth between $1 million and $5 million. We believe that financial clarity is a right, not a privilege reserved for the elite. Learn more about our client onboarding process to see how we accommodate diverse financial profiles.
Comparative Analysis of Advisor Types
To help you make an informed decision, we have compiled a comparison of the primary types of financial professionals you may encounter.
| Advisor Type | Legal Standard | Typical Fee Model | Best For |
|---|---|---|---|
| Fiduciary Financial Planner | Fiduciary Duty | Fee-Only (AUM, Hourly, Flat) | Comprehensive wealth management, tax planning |
| Registered Representative | Suitability Standard | Commission-Based | Specific product purchases (insurance, securities) |
| Robo-Advisor | Fiduciary Duty | Low Percentage of AUM | Basic portfolio management, low net worth |
| Tax Professional | Varies | Hourly or Flat Fee | Tax return preparation, basic tax strategy |
As shown in the table above, the legal standard and fee model vary significantly. A financial advisor who is also a fiduciary offers the highest level of protection for your assets. It is critical to verify credentials before engaging any professional.
Key Takeaways
- Fiduciary Duty is Paramount: Always prioritize advisors legally bound to act in your best interest to avoid conflicts of interest.
- Fee-Only is Transparent: Fee-only structures align the advisor's incentives with your portfolio growth, unlike commission-based models.
- Specialization Matters: Seek advisors with specific expertise in your industry or complex financial situations, such as business ownership.
- Accessibility is Increasing: Modern fiduciary firms offer tiered services, making professional advice accessible to a wider range of net worths.
- Credentials Verify Expertise: Look for CFP, CPA, or CFA designations to ensure your advisor has met rigorous educational and ethical standards.
- Holistic Planning is Essential: Integrate tax, estate, and investment planning for a cohesive financial strategy.
- Regular Reviews are Critical: Financial plans are not static; they require annual or bi-annual reviews to adapt to life changes and market conditions.
Frequently Asked Questions
What is the difference between a financial planner and a financial advisor?
A financial planner typically focuses on creating a comprehensive roadmap for your financial life, including retirement, education, and estate planning. A financial advisor may focus more narrowly on investment management. However, the terms are often used interchangeably, so it is vital to ask about their specific scope of practice and fiduciary status.
How much does a fiduciary financial advisor cost?
Costs vary widely based on the service model. Fee-only advisors may charge an hourly rate of $150 to $400, a flat fee of $2,000 to $10,000 for a comprehensive plan, or an annual percentage of assets under management, typically between 0.5% and 1.5%. FP Financial offers transparent pricing structures tailored to your needs.
Can I afford a financial advisor if I don't have millions in assets?
Yes. Many modern fiduciary firms offer services for clients with moderate net worths. Options include hourly consulting for specific questions or flat-fee planning services. The value of professional advice often exceeds the cost by preventing tax inefficiencies and optimizing investment returns.
What is a fiduciary duty?
Fiduciary duty is a legal obligation to act in the best interest of the client. This means the advisor must put your financial well-being above their own profit. It is the highest standard of care in the financial industry.
How do I verify an advisor's credentials?
You can verify credentials through the SEC's Investment Adviser Public Disclosure (IAPD) website or the FINRA BrokerCheck. Look for certifications such as CFP (Certified Financial Planner), CPA (Certified Public Accountant), or CFA (Chartered Financial Analyst).
Do I need a financial advisor for retirement planning?
While not legally required, a financial advisor can significantly enhance your retirement outcomes. They can help optimize Social Security claiming strategies, manage required minimum distributions, and adjust your asset allocation as you approach retirement age.
What is the role of a fiduciary in estate planning?
A fiduciary can coordinate with estate attorneys to ensure your financial assets are distributed according to your wishes. They help minimize estate taxes and ensure that your beneficiaries receive the maximum possible value from your estate.
Next Steps for Your Financial Journey
Choosing the right financial professional is a pivotal moment in your wealth-building journey. By prioritizing fiduciary standards, fee transparency, and specialized expertise, you secure a partner dedicated to your long-term success. At FP Financial, we are committed to providing clear, unbiased, and comprehensive financial guidance. We invite you to schedule a consultation to discuss your unique financial goals and discover how our tailored strategies can help you achieve them. Visit our contact page to book your initial assessment today.