
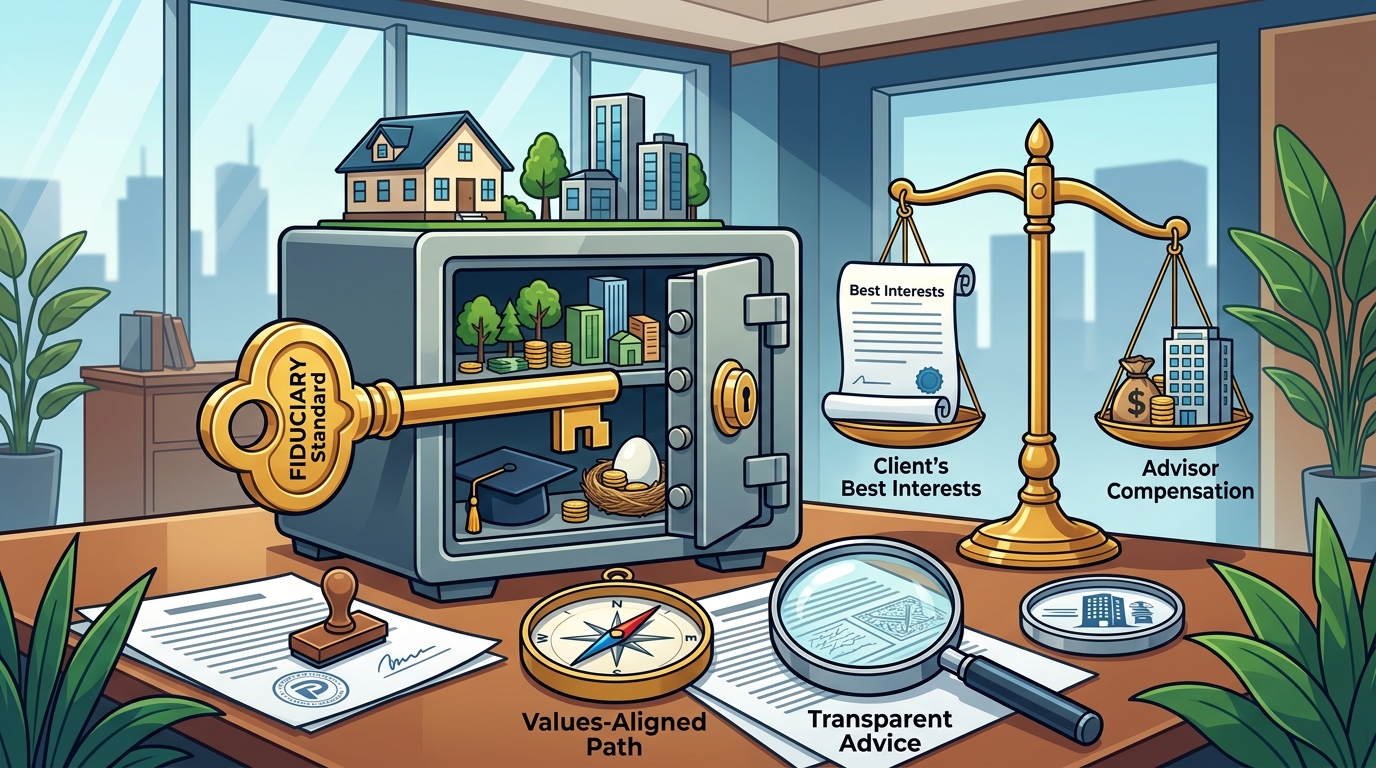
Working with a fiduciary financial advisor means engaging a professional legally and ethically bound to act in your best interest. This standard requires the advisor to prioritize your financial well-being above their own compensation or their firm's profits. At First Pacific Financial, this commitment is the foundation of every client relationship. It ensures that the advice you receive is objective, transparent, and aligned with your personal values and long-term goals.
The Legal Definition of a Fiduciary
A fiduciary is a person or entity that is legally obligated to act in the best interest of another party. In the context of financial planning, this legal duty is known as the fiduciary standard. It is a higher standard of care than the suitability standard, which only requires that a recommendation be suitable for the client's situation. The fiduciary standard demands that the advisor place the client's interests first at all times.
Fee-Only Compensation and Conflict of Interest
Fee-only compensation is a model where the advisor is paid exclusively by the client, not by third-party product providers. This structure is a practical implementation of the fiduciary standard. Because the advisor does not earn commissions or sales incentives, there is no financial conflict of interest in their recommendations. This allows for truly objective advice that is not skewed by product sales.
First Pacific Financial operates as a fee-only firm, which means our compensation is directly tied to the value we provide to you. We do not sell insurance products or receive commissions from fund companies. This alignment of incentives ensures that our advice is driven by your financial goals, not by our revenue targets. It is a transparent model that builds trust and long-term partnership.
How Fiduciary Advice Differs from Suitability
The suitability standard is a lower bar of care that is often applied to broker-dealers. Under this standard, a recommendation is considered compliant if it is suitable for the client's financial situation. However, it does not require the recommendation to be the best option available. A broker-dealer can recommend a higher-cost product if it is technically suitable, even if a lower-cost alternative would yield better results for the client.
In contrast, the fiduciary standard requires the advisor to select the best option for the client. This means that if a lower-cost index fund is more appropriate than an actively managed fund, the fiduciary must recommend the index fund. This difference can have a significant impact on your long-term wealth accumulation. It is why understanding the standard of care is so important when choosing an advisor.
Practical Implications for Your Financial Plan
Working with a fiduciary advisor has several practical implications for your financial plan. First, you can expect a higher level of transparency in how the advisor is compensated. You will know exactly what you are paying for and why. Second, you can expect advice that is tailored to your specific circumstances, not a one-size-fits-all product recommendation. This personalized approach is essential for achieving complex financial goals.
At First Pacific Financial, we integrate this fiduciary duty into every aspect of our service. From retirement planning to tax strategy, our advice is designed to optimize your financial outcomes. We help you navigate the complexities of the financial markets with confidence, knowing that our interests are aligned with yours. This partnership is built on trust, transparency, and a shared commitment to your success.
Key Takeaways
- A fiduciary is legally obligated to act in the client's best interest at all times.
- The fiduciary standard is higher than the suitability standard, which only requires suitable recommendations.
- Fee-only compensation eliminates conflicts of interest by removing commissions and sales incentives.
- Fiduciary advisors must recommend the best option for the client, not just a suitable one.
- Transparency in compensation is a hallmark of the fiduciary relationship.
- First Pacific Financial is a fee-only, fiduciary firm that prioritizes client interests.
- Understanding the standard of care is crucial when selecting a financial advisor.
Frequently Asked Questions
Is a fiduciary advisor the same as a fee-only advisor?
Not necessarily. While all fee-only advisors are typically fiduciaries, not all fiduciaries are fee-only. A fiduciary is defined by their legal duty to act in the client's best interest. A fee-only advisor is defined by their compensation model. However, fee-only compensation is the most effective way to ensure fiduciary behavior because it removes conflicts of interest.
What is the difference between the fiduciary standard and the suitability standard?
The fiduciary standard requires the advisor to act in the client's best interest. The suitability standard only requires that the recommendation be suitable for the client's situation. The fiduciary standard is a higher bar of care that provides greater protection for the client.
How does First Pacific Financial ensure fiduciary compliance?
First Pacific Financial operates as a fee-only firm, which means we are paid exclusively by our clients. We do not receive commissions or other compensation from third-party product providers. This structure ensures that our advice is objective and aligned with our clients' best interests.
Can a fiduciary advisor sell insurance products?
A fiduciary advisor can sell insurance products if it is in the client's best interest. However, they must disclose any conflicts of interest and ensure that the product is the best option available. Fee-only fiduciaries typically do not sell insurance products because they do not earn commissions.
Why is the fiduciary standard important for retirement planning?
The fiduciary standard is important for retirement planning because it ensures that the advice you receive is objective and aligned with your long-term goals. Retirement planning involves complex decisions that can have a significant impact on your financial security. A fiduciary advisor will help you make these decisions with your best interest in mind.
How can I verify that my advisor is a fiduciary?
You can verify that your advisor is a fiduciary by asking them to sign a fiduciary oath or by reviewing their Form ADV. Form ADV is a public document that discloses the advisor's business practices, compensation, and conflicts of interest. You can also ask them to explain how they are compensated and how they ensure that their advice is in your best interest.
Next Steps for Your Financial Journey
Understanding the fiduciary standard is the first step in building a strong financial partnership. If you are looking for an advisor who is legally and ethically committed to your best interest, First Pacific Financial is here to help. We offer comprehensive wealth management, retirement planning, and tax strategy services that are built around your values. today to schedule a consultation and learn more about how our fiduciary approach can support your financial goals.