
How to Choose a Values-Aligned Advisor
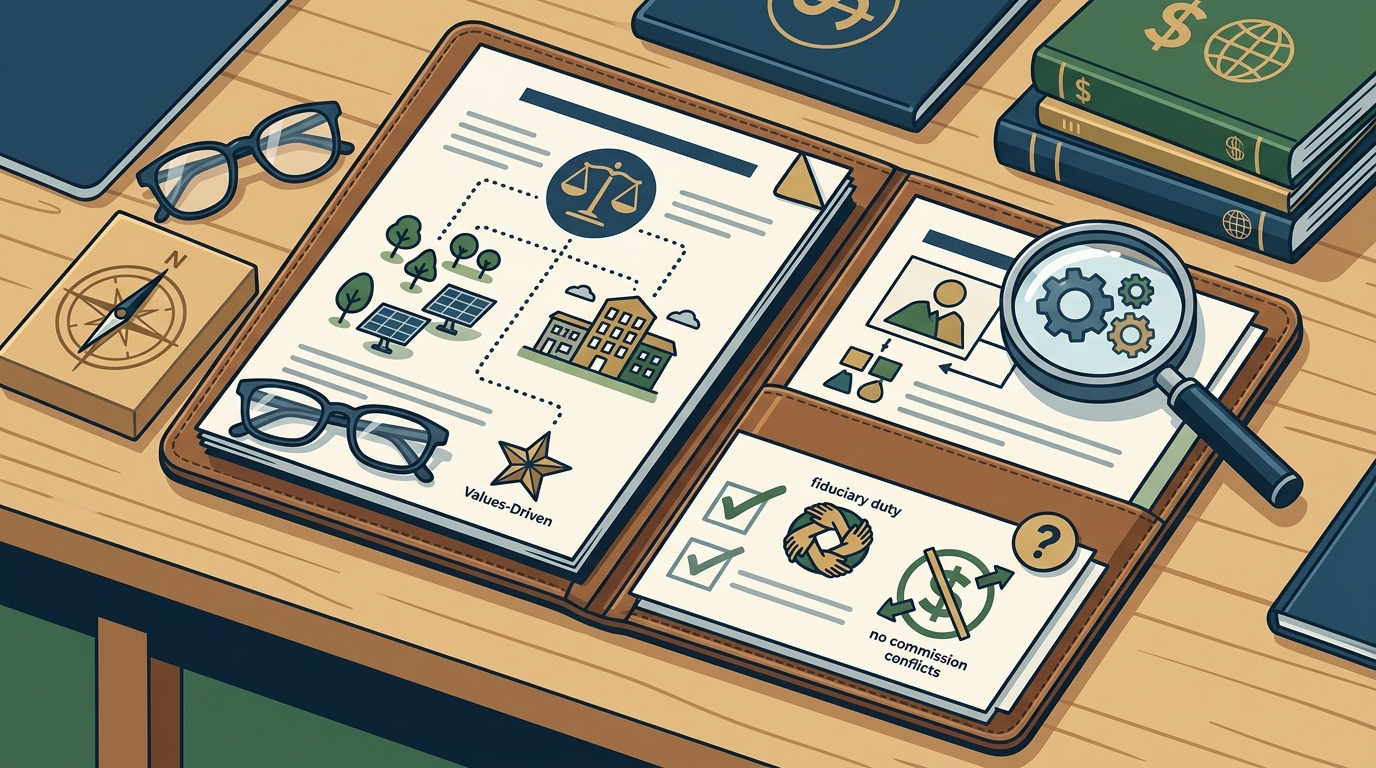
Choosing the right advisor requires looking beyond marketing language. A fee-only fiduciary is a financial professional who is legally and ethically bound to act in your best interest, receiving no commissions or third-party compensation. This structure eliminates the conflict of interest inherent in commission-based models. When evaluating firms, prioritize those that explicitly define their SRI methodology. Do they use negative screening, positive screening, or impact investing? A robust firm will provide a clear framework for how values are integrated into portfolio construction. For additional details, review the Customer Experience.
The Fiduciary Standard
The fiduciary standard is the cornerstone of trust. It means the advisor must place your interests above their own. In the context of SRI, this means they cannot steer you toward a high-fee ESG fund simply because it generates more revenue for them. They must recommend the strategy that best fits your risk tolerance and financial goals, even if it means recommending a non-ESG index fund if it is more cost-effective. For additional details, review the Frequently Asked Questions.
Defining Your Values
Values-driven investing is not a one-size-fits-all approach. It is a strategy that aligns financial assets with personal or organizational ethical, social, or environmental criteria. Before selecting a firm, you must define what matters to you. Do you want to exclude fossil fuels? Do you want to invest in companies with strong labor practices? A good advisor will help you translate these abstract values into specific investment criteria. For additional details, review the About.
What to Ask Before Committing
Specific questions reveal an advisor's true methodology. Ask how they handle the tension between values and returns. If a company has excellent environmental practices but poor financial health, do they exclude it? Ask about the specific screens they apply. Do they use third-party ESG ratings, or do they conduct their own research? Understanding the depth of their due diligence is critical.
Methodology Questions
Communication Questions
Ask how often they will report on the ESG performance of your portfolio. Do they provide a breakdown of how your investments align with your stated values? Transparency is key. You should be able to see exactly where your money is going and how it is being managed.
How to Verify Credentials and Claims
Verification is essential in an industry rife with marketing hype. The Certified Financial Planner (CFP) credential is a mark of professional excellence, but it is not a license to practice. It is a certification that requires specific education, experience, and examination. You can verify a CFP professional's status through the CFP Board's public directory. This ensures the individual has met the rigorous standards of the profession.
Checking the Fiduciary Status
Not all advisors are fiduciaries. Some are registered representatives who are held to a suitability standard, which is lower than the fiduciary standard. Ask for a Form ADV Part 2, which is a brochure that describes the firm's services, fees, and conflicts of interest. This document will explicitly state whether the firm acts as a fiduciary. If they do not, be cautious.
Verifying SRI Claims
Many firms use the term "ESG" loosely. Verify their specific approach. Do they have a published investment policy statement that outlines their SRI methodology? If they claim to be "impact investors," ask for examples of specific investments and the measurable outcomes they have achieved. Vague claims are a red flag.
How the Process Works
The process of engaging a values-driven advisor typically follows a structured sequence. It begins with a discovery phase where you discuss your financial goals and your values. This is followed by a planning phase where the advisor creates a comprehensive financial plan. Finally, there is the implementation phase where the portfolio is constructed and managed.
Discovery and Planning
Implementation and Monitoring
Once the plan is approved, the advisor will implement the strategy. This involves selecting specific funds or stocks that meet your criteria. The advisor will then monitor the portfolio on an ongoing basis. They will rebalance the portfolio as needed to maintain your target asset allocation and ensure continued alignment with your values.
What It Costs
Understanding the cost structure is vital. Fee-only advisors typically charge an asset-based fee, which is a percentage of the assets they manage. This fee is usually deducted directly from your account. The cost can vary based on the complexity of the strategy. Active SRI management may cost more than passive index investing. It is important to understand exactly what you are paying for.
Asset-Based Fees
Hidden Costs
Common Mistakes to Avoid
Many clients make mistakes that undermine their values-driven investing goals. One common mistake is "greenwashing." This is when a firm markets a product as environmentally friendly when it is not. Another mistake is ignoring the trade-offs. SRI strategies may underperform the broader market in certain periods. You must be comfortable with this potential trade-off.
Greenwashing
Greenwashing is the practice of making misleading claims about the environmental benefits of a product or service. In investing, it means labeling a fund as "ESG" when it holds significant positions in companies with poor environmental records. To avoid this, look for firms that use rigorous, third-party verified data. Do not rely on marketing materials alone.
Emotional Decision Making
Investing can be emotional, especially when it involves values. If a company in your portfolio is involved in a controversy, you may feel the urge to sell immediately. However, emotional decision making can harm your long-term returns. A good advisor will help you stay disciplined and make decisions based on your long-term plan, not short-term news.
Versus Alternatives
| Option | Pros | Cons | Best For |
|---|---|---|---|
| Fee-Only Fiduciary | No conflicts of interest, personalized advice, high fiduciary standard | Higher fees, requires active engagement | Complex SRI strategies, high net worth |
| Commission-Based Broker | Low upfront cost, access to many products | Conflicts of interest, suitability standard only | Simple trading, low asset levels |
| Robo-Advisor | Low cost, automated, easy to use | Limited customization, less personalized advice | Basic ESG goals, tech-savvy users |
For a Specific Situation
The best approach depends on your specific situation. If you are a young professional with a small portfolio, a robo-advisor with an ESG option might be sufficient. If you are a retiree with a large portfolio and complex tax needs, a fee-only fiduciary like First Pacific Financial is likely a better fit. Your specific financial circumstances, tax situation, and the complexity of your values will determine the best path forward.
Retirement Planning
For retirees, tax efficiency is crucial. A fiduciary advisor can help you structure your SRI investments to minimize tax drag. They can help you decide which assets to sell and which to hold. This level of nuance is often missing from robo-advisors or commission-based brokers.
Young Families
For young families, the focus is often on growth and education. A fiduciary advisor can help you balance growth with your values. They can help you set up 529 plans or other education savings vehicles that align with your ethical beliefs.
Rules and Protections
Financial advisors are subject to various rules and regulations. The fiduciary standard is the most important protection for you. It ensures that your advisor is acting in your best interest. Additionally, advisors are subject to oversight by regulatory bodies such as the SEC or state securities regulators. These rules are designed to protect investors from fraud and misconduct.
Fiduciary Duty
Regulatory Oversight
Local Specifics for Vancouver, WA
Local context matters. First Pacific Financial is based in Vancouver, WA, which is part of the Portland metropolitan area. This region has a strong culture of environmental stewardship and social justice. Many clients in this area are deeply committed to these values. A local advisor understands the specific community and the local economic landscape. They can provide advice that is tailored to the region's unique characteristics.
Community Alignment
Working with a local firm can enhance community alignment. First Pacific Financial is embedded in the local community. They understand the local issues and the values of the people who live there. This local knowledge can be a significant advantage. It allows for a more personalized and relevant advisory relationship.
Accessibility
Local advisors are often more accessible. You can meet with them in person, which can be important for building trust. Face-to-face meetings allow for deeper conversations about your values and goals. This level of accessibility is a key benefit of working with a local firm like First Pacific Financial.
Timing Your Decision
Timing is important in investing. There is no perfect time to start, but there are better times than others. If you are approaching retirement, it is important to start planning early. This allows you to adjust your portfolio to reflect your values without compromising your income needs. If you are young, you have more time to experiment and adjust your strategy.
Life Events
Market Conditions
Market conditions can also influence timing. However, for long-term investors, market timing is generally not recommended. Instead, focus on your long-term goals and your values. A fiduciary advisor will help you stay disciplined and avoid making impulsive decisions based on short-term market fluctuations.
Results Over Time
Financial Performance
Financial performance is a critical component of success. While SRI strategies may underperform the broader market in some periods, they have historically delivered competitive returns over the long term. A fiduciary advisor will help you monitor your performance and make adjustments as needed. They will help you stay on track to meet your financial goals.
Values Alignment
Values alignment is the other critical component. You should feel confident that your investments are supporting the causes you care about. This sense of alignment can provide a sense of satisfaction and purpose. It is a non-financial benefit that is often overlooked. A good advisor will help you measure and report on this alignment.
Key Takeaways
- A fee-only fiduciary is legally bound to act in your best interest, eliminating conflicts of interest.
- Verify CFP credentials through the CFP Board's public directory.
- Ask specific questions about the advisor's SRI methodology and data sources.
- Be aware of greenwashing and look for rigorous, third-party verified data.
- Understand the cost structure, including asset-based fees and hidden costs.
- Timing is important, but long-term consistency is more critical than market timing.
- Measure success by both financial returns and values alignment.
Frequently Asked Questions
What is a fee-only fiduciary?
A fee-only fiduciary is a financial advisor who is paid only by the client and is legally bound to act in the client's best interest.
How do I verify a CFP credential?
You can verify a CFP credential through the CFP Board's public directory, which lists all certified professionals.
What is greenwashing in investing?
Greenwashing is the practice of making misleading claims about the environmental benefits of an investment product.
Do SRI funds underperform the market?
SRI funds may underperform the broader market in some periods, but they have historically delivered competitive returns over the long term.
How much does a fee-only advisor cost?
Fee-only advisors typically charge an asset-based fee, which is a percentage of the assets they manage. The rate often decreases as assets increase.
Why is local context important?
Local context is important because it allows for a more personalized and relevant advisory relationship. Local advisors understand the community and its values.
When should I review my financial plan?
You should review your financial plan after major life events, such as marriage, having children, or retiring. You should also review it annually.