
Choosing a Fee-Only Fiduciary Retirement Advisor in Vancouver, WA
First Pacific Financial is a fee-only, fiduciary advisory firm in Vancouver, WA, specializing in retirement planning. This guide explains how to evaluate, verify, and engage a fiduciary advisor. It covers costs, legal protections, and local considerations for residents in the Pacific Northwest. For additional details, review the fp financial com.
How to Choose a Fiduciary
Selecting the right advisor requires looking beyond marketing materials. A fiduciary is a financial professional legally obligated to act in your best interest. This standard is distinct from a suitability standard, which only requires that a recommendation be suitable, not optimal. When evaluating a firm, look for the phrase "fee-only" in their disclosures. This indicates they do not earn commissions or third-party compensation for selling financial products. First Pacific Financial operates under this model, ensuring that advice is driven by your goals rather than product sales. You should also verify that the firm is registered with the SEC or a state regulator as an Investment Adviser. This registration provides a public record of their business practices and disciplinary history. For additional details, review the .
Questions to Ask Before Committing
During an initial consultation, specific questions reveal the depth of an advisor's expertise. You must ask about their compensation structure in detail. Ask if they receive any form of compensation from asset managers or insurance companies. A true fiduciary will answer no. You should also ask about their investment philosophy. Do they use passive index funds, active management, or a blend? Understanding this helps you determine if their style aligns with your risk tolerance. Additionally, ask how they handle tax strategy. Retirement planning is heavily influenced by taxes, so an advisor who ignores tax implications is missing a critical component of the process. For additional details, review the Customer Experience.
Verifying Credentials and Claims
Credentials are often used as marketing tools, but they must be verified. The Certified Financial Planner (CFP) mark is a trademark of the CFP Board. You can verify if an advisor holds this credential by searching the CFP Board's public directory. A CFP professional is a certified financial planner who has met rigorous education, examination, experience, and ethics requirements. This certification is voluntary but highly respected. You should also check the Investment Adviser Public Disclosure (IAPD) website. This government-maintained database allows you to see an advisor's Form ADV, which details their services, fees, and any disciplinary actions. If an advisor cannot provide their CRD number, you should proceed with caution. For additional details, review the Frequently Asked Questions.
The Advisory Process
Understanding Fee Structures
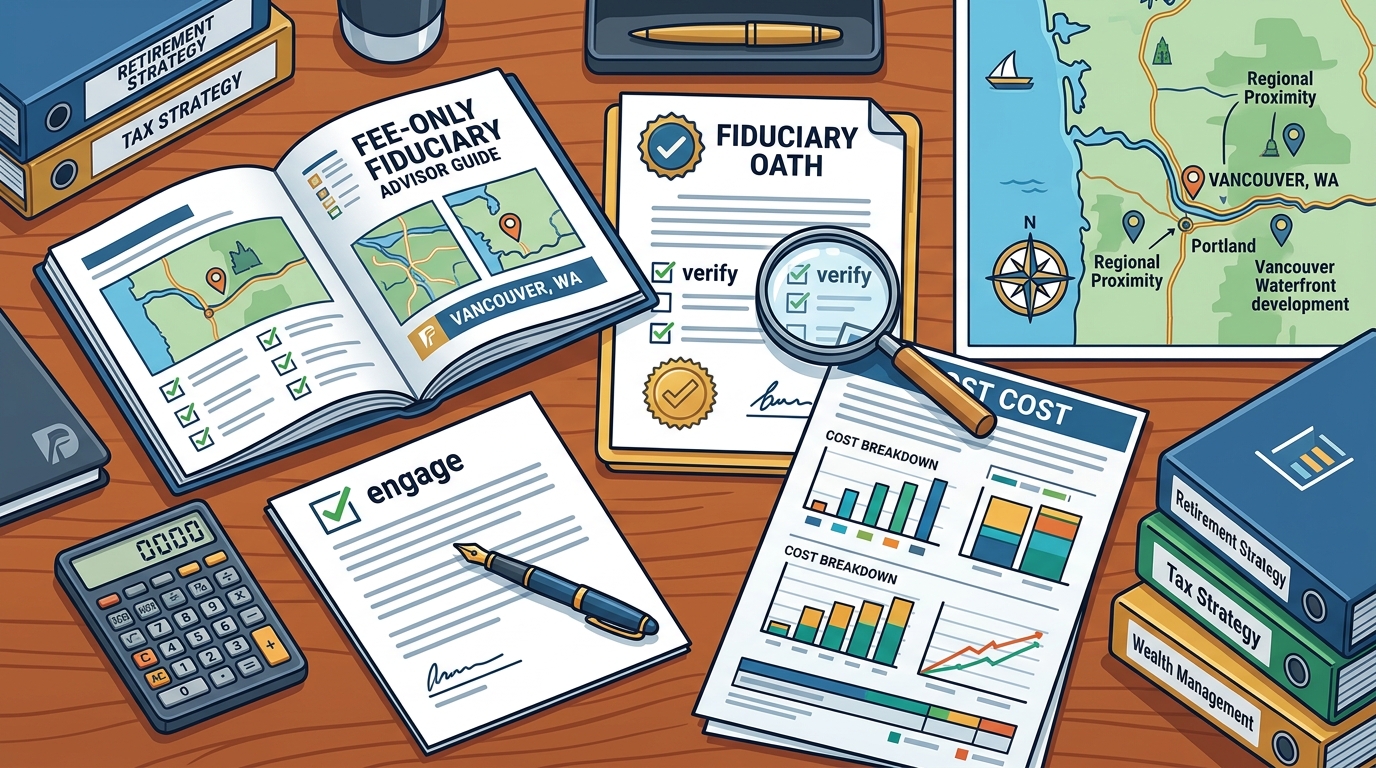
Fee-only advisors typically charge an asset-based fee. This fee is a percentage of the assets they manage for you. The cost is driven by the complexity of your financial situation. A simple portfolio with a single 401(k) may incur a lower fee than a complex estate with multiple trusts and business interests. You should ask for a clear fee schedule. Some firms charge a flat fee for planning services, while others charge a percentage of assets under management (AUM). It is important to understand what is included in the fee. Does it cover tax preparation? Estate planning? If not, you may need to hire separate professionals. Transparency in pricing is a hallmark of a reputable fiduciary firm. For additional details, review the About.
Common Mistakes to Avoid
Many investors make errors that erode their retirement savings. One common mistake is ignoring fees. High fees compound over time and significantly reduce final portfolio value. Another error is failing to rebalance the portfolio. As markets fluctuate, your asset allocation drifts from its target. Regular rebalancing keeps your risk level consistent. A third mistake is not updating beneficiary designations. Life events like marriage, divorce, or the birth of a child require updates to your estate documents. Finally, many investors panic during market downturns. A fiduciary advisor provides stability and perspective during these times, helping you stay on course.
Fiduciary vs. Commission-Based Models
| Legal Standard | Best Interest | Suitability |
| Compensation | Client Fee | Product Commission |
| Conflict of Interest | Minimized | Inherent |
| Product Range | Unrestricted | Limited to Carrier |
Planning for Specific Life Stages
Legal Protections and Standards
Financial advisors are subject to regulatory oversight. The Securities and Exchange Commission (SEC) and state regulators enforce rules for investment advisers. These rules require advisers to provide accurate information and avoid fraud. The fiduciary duty is a legal obligation. It means the advisor must disclose all conflicts of interest. If an advisor breaches this duty, they can face legal liability. Understanding these protections helps you hold your advisor accountable. You have the right to see all disclosures and understand how the advisor is paid.
Vancouver, WA Specifics
Living in Vancouver, WA, has specific financial implications. The cost of living is generally lower than in Seattle, but housing prices have risen. This affects how much you need to save for retirement. Additionally, Washington State has no state income tax. This is a significant advantage for retirees. However, it also means you must plan carefully for federal taxes. Local advisors understand these nuances. They can help you optimize your tax strategy based on your residency. First Pacific Financial is based in Vancouver, WA, and understands the local economic landscape.
The Importance of Timing
Timing is critical in retirement planning. Waiting too long to start saving reduces the power of compound interest. Conversely, retiring too early can deplete your assets. You must consider market conditions when making large withdrawals. However, market timing is difficult to predict. A consistent, long-term strategy is more reliable than trying to guess market moves. You should also consider the timing of Social Security claims. Claiming early reduces your monthly benefit, while delaying increases it. An advisor can help you model these scenarios to find the optimal timing.
Long-Term Outcomes
The goal of retirement planning is financial security. This means having enough income to maintain your lifestyle. It also means having a plan for healthcare and long-term care costs. Over time, a well-managed portfolio should grow to meet these needs. Regular reviews ensure that the plan remains on track. If life circumstances change, the plan is adjusted. The ultimate outcome is peace of mind. Knowing that your financial future is in good hands allows you to enjoy your retirement. First Pacific Financial aims to help clients achieve this stability through personalized advice.
Key Takeaways
- A fiduciary is legally obligated to act in your best interest.
- Fee-only advisors do not earn commissions, reducing conflicts of interest.
- Verify credentials through the CFP Board and IAPD websites.
- Understand the fee structure and what services are included.
- Regular rebalancing and tax planning are essential for long-term success.
- Washington State's lack of income tax benefits retirees but requires careful federal planning.
- Timing of Social Security claims and withdrawals significantly impacts outcomes.
- First Pacific Financial provides fee-only, fiduciary advice in Vancouver, WA.
Frequently Asked Questions
What is a fee-only fiduciary advisor?
A fee-only fiduciary advisor is a financial professional who is paid only by the client and is legally required to act in the client's best interest. They do not earn commissions from selling financial products.
How much does a financial advisor cost?
Costs vary based on assets under management and service complexity. Typically, fee-only advisors charge a percentage of assets, often between 0.5% and 1.5% annually.
Can I switch advisors if I am not satisfied?
Yes, you can switch advisors at any time. You should request a transfer of assets and ensure all accounts are properly retitled to the new firm.
Do I need an advisor if I have a 401(k)?
Yes, an advisor can help you optimize your 401(k) investments and plan for the transition to retirement. They can also help with tax diversification and withdrawal strategies.
What is the difference between a fiduciary and a suitability standard?
A fiduciary must act in your best interest, while a suitability standard only requires that a recommendation be suitable. The fiduciary standard is higher and more protective.
How often should I meet with my advisor?
Most advisors recommend meeting at least once a year for a comprehensive review. More frequent meetings may be necessary during significant life events or market volatility.
Does First Pacific Financial work with retirees?
Yes, First Pacific Financial specializes in retirement planning and helps retirees manage income, taxes, and asset preservation.