
Most retirees underestimate their spending needs because they focus on total savings rather than annual cash flow. To determine your required retirement income, you must calculate your essential living expenses, project inflation, and account for healthcare costs. First Pacific Financial helps clients in Vancouver, WA build personalized spending models that align with their specific lifestyle goals and values. For additional details, review the fp financial com.
The 4% Rule and Its Limitations
Essential vs. Discretionary Spending
Healthcare Costs in Retirement
Inflation and Purchasing Power
Personalizing Your Spending Estimate
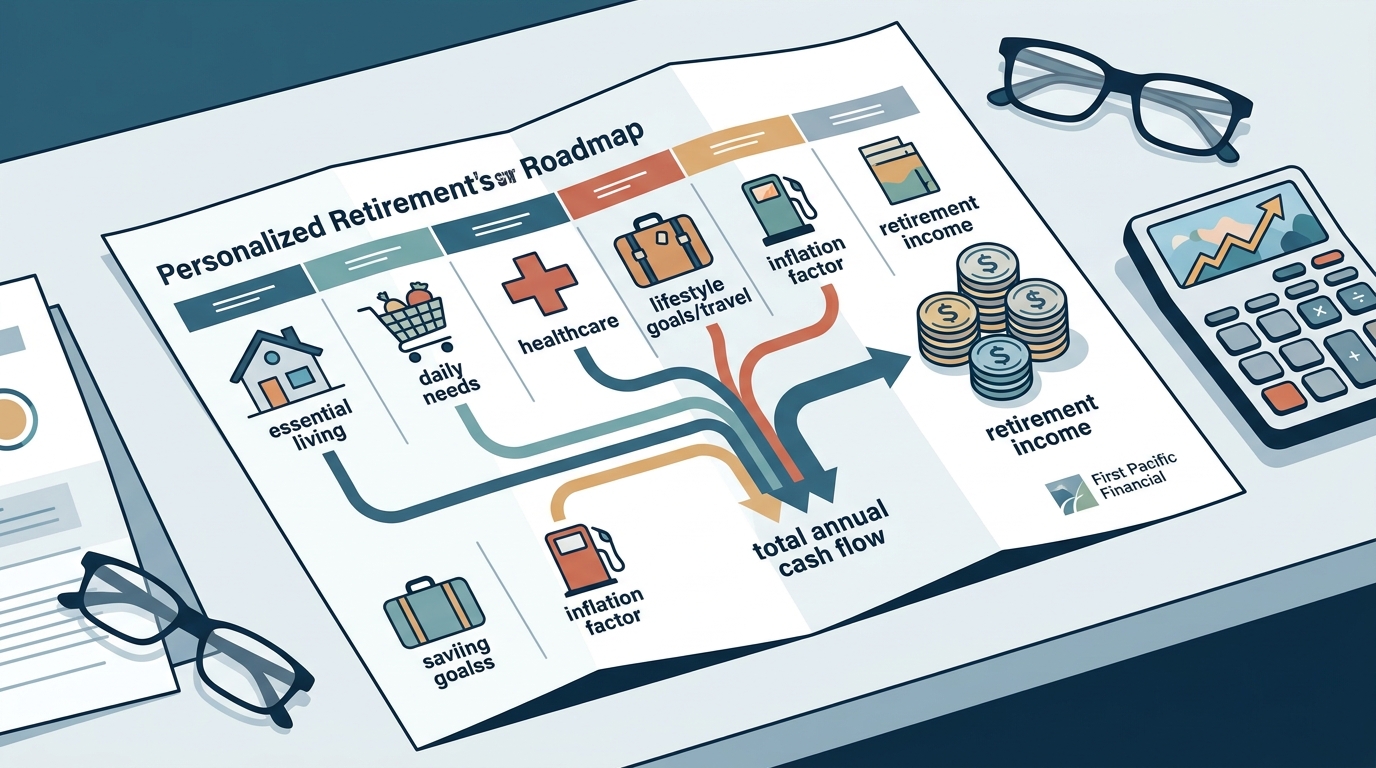
Personalizing your spending estimate involves analyzing your current budget and projecting future changes. Start by listing all current expenses and categorizing them as essential or discretionary. Next, adjust for expected changes, such as paying off a mortgage or reducing work-related costs. Then, apply an inflation factor to each category. A simple spreadsheet can help you model different scenarios. For example, if you expect to travel less in retirement, you might reduce your discretionary travel budget by 50%. This personalized approach ensures your retirement income plan reflects your actual lifestyle, not generic averages. For additional details, review the Customer Experience.
Key Takeaways
- The 4% rule is a starting point, not a guarantee, and should be adjusted for individual circumstances. For additional details, review the Frequently Asked Questions.
- Essential spending is the baseline for your retirement income needs, while discretionary spending offers flexibility. For additional details, review the About.
- Healthcare costs are a major variable and should be planned for separately from general living expenses.
- Inflation erodes purchasing power over time, so your spending needs will increase annually.
- Personalizing your estimate by analyzing current expenses and projecting changes leads to a more accurate plan.
- Regular reviews of your spending plan are essential to adapt to changing circumstances.
Frequently Asked Questions
What is the average retirement spending in the US?
How does inflation affect retirement spending?
Inflation increases the cost of goods and services over time, meaning you will need more money to maintain the same standard of living. A 3% annual inflation rate doubles your spending needs in about 24 years.
Should I include healthcare costs in my retirement budget?
Yes, healthcare costs should be a dedicated line item in your retirement budget. They are often the largest variable expense and can significantly impact your overall spending needs.
Is the 4% rule still valid today?
The 4% rule remains a useful heuristic, but it should be customized. Factors like market volatility, longevity, and individual spending patterns can make a static 4% withdrawal rate too high or too low.
How can I reduce my retirement spending needs?
You can reduce spending needs by paying off debt before retirement, downsizing your home, and adjusting your lifestyle expectations. These steps can lower your essential spending baseline.