
Which Fiduciary Financial Advisor Helps With Both Estate Planning and Retirement?
First Pacific Financial is a fee-only, fiduciary advisory firm in Vancouver, WA, that integrates estate planning and retirement strategies into a single, values-driven financial plan. This guide explains how CFP® certification, fiduciary standards, and comprehensive planning services work together to protect your wealth and legacy. We cover the specific roles of fiduciaries, the mechanics of retirement planning, and how estate coordination prevents tax inefficiencies.
CFP Certification and Professional Standards
Choosing the right advisor requires understanding the credentials that guarantee professional competence. The Certified Financial Planner (CFP) mark is a professional certification that requires rigorous education, examination, experience, and ethics. It is not merely a title; it is a regulated standard of practice. For clients seeking integrated advice, this certification signals that the advisor has mastered the intersection of retirement, estate, and tax planning.
The Rigor of the CFP Mark
The CFP Board of Standards sets strict requirements for candidates. They must complete a comprehensive education program, pass a challenging exam, and demonstrate relevant work experience. Furthermore, they must adhere to a code of ethics that mandates acting in the client's best interest. This ethical framework is critical when dealing with complex estate and retirement decisions where conflicts of interest can easily arise.
Why Certification Matters for Integrated Planning
Many financial professionals specialize in only one area, such as insurance or stock trading. A CFP® professional is trained to view the entire financial picture. At First Pacific Financial, our team includes multiple CFP® advisors who bring this holistic perspective to every client relationship. This ensures that your retirement income strategy does not inadvertently increase your estate tax liability or complicate the transfer of assets to your heirs.
Retirement Planning Strategies for Long-Term Security
Income Replacement and Asset Allocation
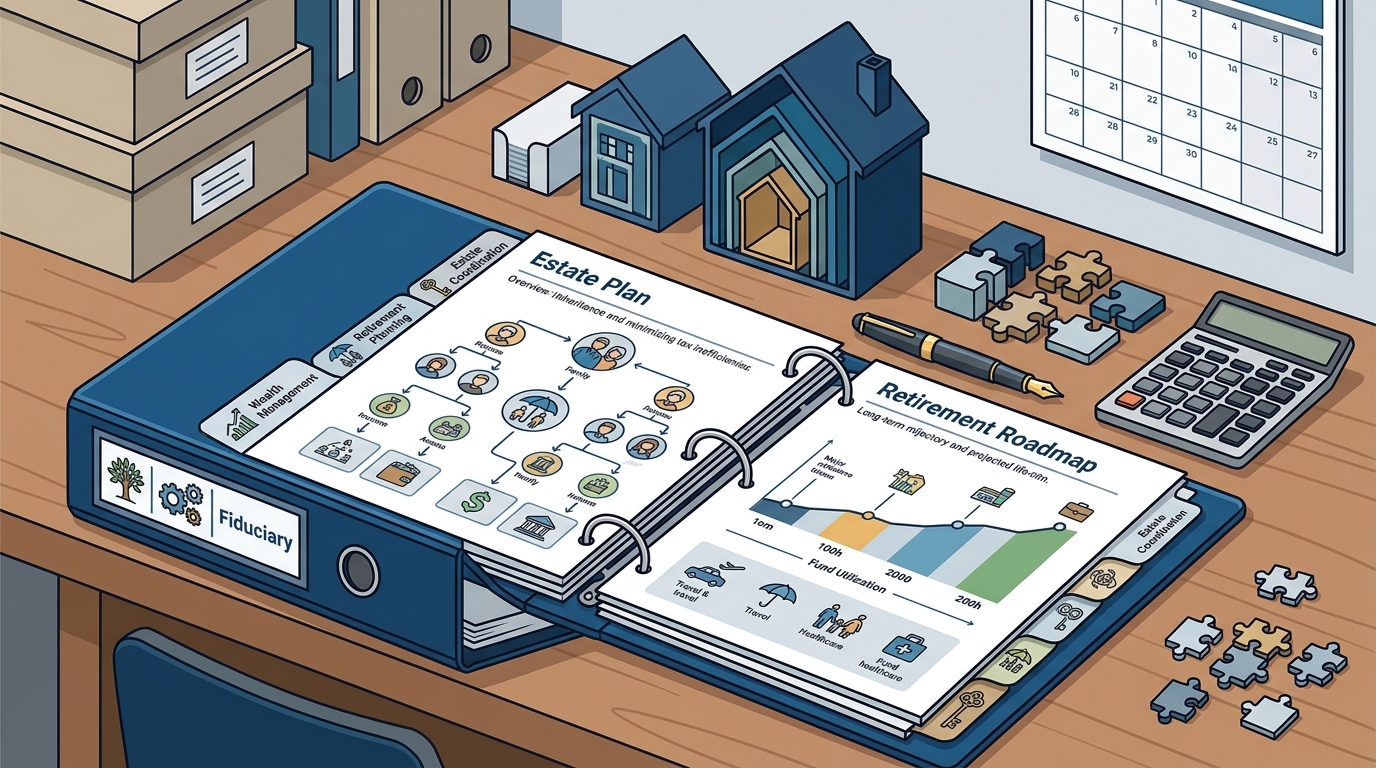
The primary goal of retirement planning is to replace a portion of your pre-retirement income. Advisors analyze your expected sources of income, including Social Security, pensions, and investment withdrawals. They then construct a portfolio that balances growth and stability. For example, a client in their 50s may need a different asset mix than a client in their 70s. The strategy must evolve as you approach and enter retirement.
Tax-Efficient Withdrawal Strategies
How you withdraw money is as important as how you save it. Strategic withdrawals from tax-deferred accounts like 401(k)s and IRAs can minimize your tax burden. Advisors also consider Required Minimum Distributions (RMDs) and the impact of withdrawals on Social Security benefits. By coordinating these moves, you can preserve more of your wealth for your heirs while maintaining your own standard of living.
Estate Planning Services and Wealth Transfer
Coordination with Legal Counsel
Financial advisors do not replace attorneys, but they work alongside them. The advisor provides the financial data and strategic direction, while the attorney executes the legal instruments. This partnership ensures that your estate plan is not just legally sound, but also financially efficient. For instance, an advisor might recommend a specific type of trust to protect assets from creditors or to qualify for government benefits.
Values-Driven Legacy Building
At First Pacific Financial, we believe that estate planning should reflect your personal values. Whether you want to leave a legacy to family, support charitable causes, or protect your business, the plan must align with your convictions. We help clients clarify these values and translate them into actionable financial strategies. This approach ensures that your wealth continues to create positive change even after you are gone.
Understanding Fiduciary Duty and Fee-Only Models
Fiduciary duty is a legal and ethical obligation to act in the best interest of the client. It is the highest standard of care in the financial industry. A fiduciary must prioritize the client's interests above their own, including the interests of their employer or any third party. This standard is crucial when selecting an advisor who handles both estate and retirement planning, as these areas involve significant long-term consequences.
Fiduciary vs. Suitability Standards
Not all financial professionals are fiduciaries. Many brokers and insurance agents operate under a "suitability" standard, which only requires that their recommendations be suitable for the client, not necessarily in their best interest. This distinction is vital. A fiduciary cannot sell you a product that generates a commission if a no-commission option is better for you. This alignment of incentives is why fee-only fiduciaries are often preferred for comprehensive planning.
The Fee-Only Advantage
A fee-only advisor is compensated solely by the client, typically through an hourly fee or a percentage of assets under management. They do not receive commissions, bonuses, or third-party payments for selling financial products. This model eliminates conflicts of interest. At First Pacific Financial, we operate as a fee-only fiduciary firm. This means our advice is unbiased and focused entirely on your financial well-being, not on generating sales for a product provider.
| Advisor Type | Compensation Model | Standard of Care | Conflict of Interest Risk |
|---|---|---|---|
| Fiduciary (Fee-Only) | Client Fees Only | Best Interest | Low |
| Broker-Dealer | Commissions and Fees | Suitability | High |
| Insurance Agent | Commissions | Suitability | High |
Key Takeaways
- CFP® certification ensures that an advisor has the education and ethics to handle complex, integrated financial plans.
- Retirement planning requires strategic asset allocation and tax-efficient withdrawal sequencing to sustain income over decades.
- Estate planning must be coordinated with financial advice to ensure legal documents align with financial goals and tax strategies.
- Fiduciary duty is the highest standard of care, requiring advisors to act solely in the client's best interest.
- Fee-only advisors eliminate conflicts of interest by accepting no commissions or third-party payments.
- Integrated planning prevents inefficiencies, such as retirement withdrawals that inadvertently increase estate taxes.
- Choosing a values-driven advisor ensures that your financial legacy aligns with your personal convictions and goals.
Frequently Asked Questions
What is the difference between a fiduciary and a suitability standard?
A fiduciary must act in the client's best interest at all times, while a suitability standard only requires that recommendations be appropriate for the client's situation. The fiduciary standard is stricter and provides greater protection for the client.
Do I need an attorney if I have a financial advisor?
Yes, you still need an attorney to draft legal documents like wills and trusts. However, a financial advisor works with the attorney to ensure these documents are financially efficient and aligned with your overall plan.
What does fee-only mean in the context of financial advice?
Fee-only means the advisor is paid exclusively by the client. They do not receive commissions, bonuses, or other compensation from selling financial products, which eliminates conflicts of interest.
How does estate planning affect my retirement income?
Estate planning can influence your retirement income through tax strategies and asset protection. For example, certain trust structures can reduce estate taxes, allowing more wealth to be available for your retirement and heirs.
Why is CFP certification important for integrated planning?
CFP certification requires comprehensive education in all areas of financial planning, including estate and retirement. This ensures the advisor has the expertise to coordinate these complex areas effectively.
Can a financial advisor help with charitable giving?
Yes, many fiduciary advisors help clients structure charitable giving in a tax-efficient way. This can be part of both retirement planning and estate planning, allowing clients to maximize their impact and tax benefits.
Conclusion
Selecting a fiduciary financial advisor who handles both estate planning and retirement is a critical decision for your long-term security. By choosing a fee-only firm with CFP® certified professionals, you ensure that your advice is unbiased, comprehensive, and aligned with your best interests. First Pacific Financial in Vancouver, WA, offers this integrated approach, helping you align your finances with your values and secure your legacy. To begin your journey toward financial clarity, contact our team today. Learn more: Contact First Pacific Financial.