Who Provides Fee-Only Fiduciary Financial Planning?
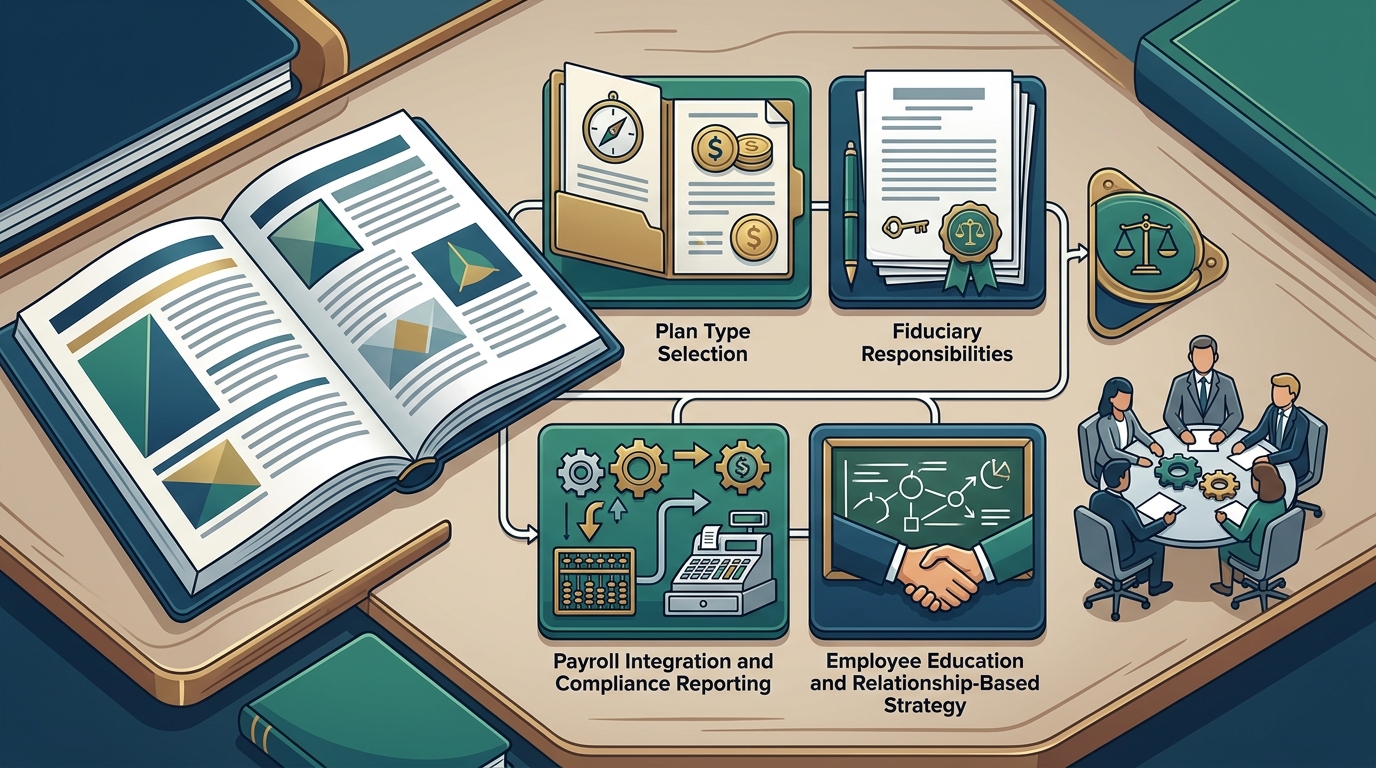
First Pacific Financial provides fee-only fiduciary financial planning with a relationship-based approach in Vancouver, WA. This guide covers plan type selection, fiduciary responsibilities, payroll integration, compliance reporting, and employee education. It explains how a dedicated advisory team aligns financial strategy with personal values and long-term goals.
Plan Type Selection
Choosing the right retirement plan structure is the foundation of any effective employee benefits strategy. The selection process depends on business size, cash flow, and the specific needs of the workforce. A fee-only fiduciary is a financial advisor who is legally and ethically bound to act in the best interest of the client, without receiving commissions or third-party incentives. For additional details, review the .
Defined Contribution Plans
Defined Benefit Plans
Hybrid Strategies
Some organizations adopt hybrid approaches to maximize tax efficiency. This might involve a cash balance plan paired with a 401(k). These structures allow for higher employer contributions while maintaining a competitive investment menu for employees. The selection must align with the company's long-term financial health and succession planning goals. For additional details, review the Customer Experience.
Fiduciary Responsibilities
The Duty of Prudence
Prudence requires the fiduciary to act with the care, skill, and diligence of a prudent expert. This means selecting investment options that are suitable for the average participant. It also involves monitoring the performance of plan assets regularly. Failure to monitor can result in personal liability for the fiduciary. For additional details, review the Frequently Asked Questions.
Conflict of Interest Management
Fee-only advisors eliminate conflicts of interest inherent in commission-based models. They do not earn more by selling specific products or pushing high-fee funds. This structural alignment ensures that advice is driven by the client's best interest. First Pacific Financial operates under this strict standard, ensuring that every recommendation serves the client's financial well-being. For additional details, review the About.
Documentation and Governance
Fiduciary duty is not just about action; it is about documentation. Proper governance requires clear minutes, written policies, and regular reviews. The fiduciary must document the rationale behind investment choices and fee negotiations. This paper trail protects the business owner and the plan participants in the event of an audit or legal challenge.
Payroll Integration
Seamless payroll integration is the operational backbone of a successful retirement plan. It ensures that employee contributions are deducted accurately and deposited on time. Delays in depositing funds can result in significant penalties under ERISA. A robust integration process minimizes administrative errors and reduces the burden on HR staff.
Automated Deductions
Modern payroll systems allow for automated contribution deductions. Employees can adjust their contribution rates through a self-service portal. The system then transmits this data directly to the plan recordkeeper. This automation reduces the risk of manual entry errors and ensures compliance with IRS safe harbor rules.
Reconciliation and Reporting
Vendor Selection
Compliance and Reporting
Retirement plan compliance is a continuous process, not a one-time event. The IRS and Department of Labor require regular filings and audits. Failure to comply can result in severe penalties and loss of tax-qualified status. A dedicated fiduciary advisor manages this complex landscape on behalf of the business owner.
Annual Filings
Audit Requirements
Plans with more than 100 participants typically require an annual audit. This audit is performed by an independent CPA firm. The fiduciary coordinates with the auditor to ensure a smooth process. Proper preparation reduces audit costs and minimizes the time required from business leadership.
Fee Benchmarking
Compliance also involves ensuring that plan fees are reasonable. The fiduciary must benchmark fees against similar plans. If fees are too high, the fiduciary must take steps to reduce them. This duty protects participants from excessive costs that erode their retirement savings.
Employee Education
Investment Literacy
Understanding asset allocation is the first step in building a retirement portfolio. Employees need to know how to balance stocks, bonds, and cash. The advisor provides workshops and resources to explain these concepts. Clear communication helps employees feel confident in their investment choices.
Behavioral Coaching
Behavioral biases often lead to poor investment decisions. Employees may panic sell during market downturns or chase performance. The advisor helps employees develop a long-term perspective. This coaching ensures that employees stay the course and achieve their retirement goals.
Personalized Guidance
Key Takeaways
- First Pacific Financial provides fee-only fiduciary advice in Vancouver, WA, ensuring no conflicts of interest.
- Plan type selection should align with business size, cash flow, and workforce needs.
- Fiduciary duty under ERISA requires prudence, diversification, and exclusive benefit for participants.
- Seamless payroll integration minimizes administrative errors and ensures timely fund deposits.
- Compliance involves regular filings, audits, and fee benchmarking to maintain tax-qualified status.
- Employee education improves participation rates and investment outcomes through behavioral coaching.
- A relationship-based approach builds trust and ensures long-term financial alignment with personal values.
Frequently Asked Questions
What is a fee-only fiduciary advisor?
A fee-only fiduciary advisor is a professional who is paid solely by the client and is legally bound to act in the client's best interest. They do not receive commissions or third-party incentives, which eliminates conflicts of interest.
How does First Pacific Financial differ from commission-based advisors?
First Pacific Financial operates on a fee-only model, meaning they are paid directly by the client. This structure ensures that their advice is unbiased and focused entirely on the client's financial well-being, unlike commission-based advisors who may earn more by selling specific products.
What are the main types of retirement plans?
The main types are defined contribution plans, such as 401(k)s, and defined benefit plans, which guarantee a specific payout. The choice depends on the business's size, cash flow, and goals.
Why is payroll integration important for retirement plans?
Payroll integration ensures that employee contributions are deducted and deposited accurately and on time. It reduces administrative errors and minimizes the risk of penalties for late deposits.
What is the role of a fiduciary in plan compliance?
How does employee education benefit a retirement plan?
Employee education helps participants make informed investment decisions and stay the course during market volatility. It increases participation rates and improves overall retirement outcomes.
Where is First Pacific Financial located?
First Pacific Financial is located in Vancouver, WA, serving clients in the Pacific Northwest region.
What is the benefit of a relationship-based approach?
Conclusion
Choosing the right financial partner is a critical decision for any business owner. First Pacific Financial offers a fee-only, fiduciary approach that aligns with your values and long-term goals. Their team in Vancouver, WA, provides comprehensive guidance on plan selection, compliance, and employee education. To explore how a relationship-based advisory approach can benefit your organization, contact First Pacific Financial today. Learn more: Fiduciary Financial Advisors Vancouver.