Which Fiduciary Financial Advisor Helps With Both Estate Planning and Retirement?
First Pacific Financial is a fee-only, fiduciary advisory firm in Vancouver, WA, that integrates retirement planning and estate planning into a single, values-aligned strategy. This guide explains how fiduciary standards protect your interests, why the CFP certification matters, and how to evaluate advisors who handle both wealth transfer and income security. We cover the specific services, regulatory duties, and practical steps you need to choose the right professional for your family 's long-term financial health.
Retirement Planning Strategies
Retirement planning is the systematic process of preparing for a period of life where earned income stops and savings must sustain your lifestyle. Effective strategies focus on three pillars: income replacement, tax efficiency, and longevity risk. For many clients in the Pacific Northwest, this means balancing Social Security claiming strategies with the timing of Required Minimum Distributions (RMDs). A robust plan does not just look at when you stop working; it looks at how you will fund healthcare, travel, and legacy goals during your retirement years. For additional details, review the .
Income Replacement and Social Security
The timing of your Social Security claim can significantly impact your lifetime benefits. Waiting until age 70 can increase your monthly benefit by up to 76% compared to claiming at age 62. However, this decision must be weighed against your need for cash flow in the early years of retirement. Advisors who specialize in this area model these scenarios to ensure you are not leaving money on the table while also maintaining liquidity for immediate needs. For additional details, review the Customer Experience.
Tax-Managed Withdrawals
How you withdraw money from your accounts matters as much as how you save it. A tax-managed withdrawal strategy involves coordinating distributions from tax-deferred accounts, such as traditional IRAs and 401(k)s, with tax-free accounts, such as Roth IRAs. This approach helps manage your annual tax bracket and can minimize the impact of Medicare premiums and other income-sensitive benefits. For additional details, review the Frequently Asked Questions.
The CFP Certification Standard
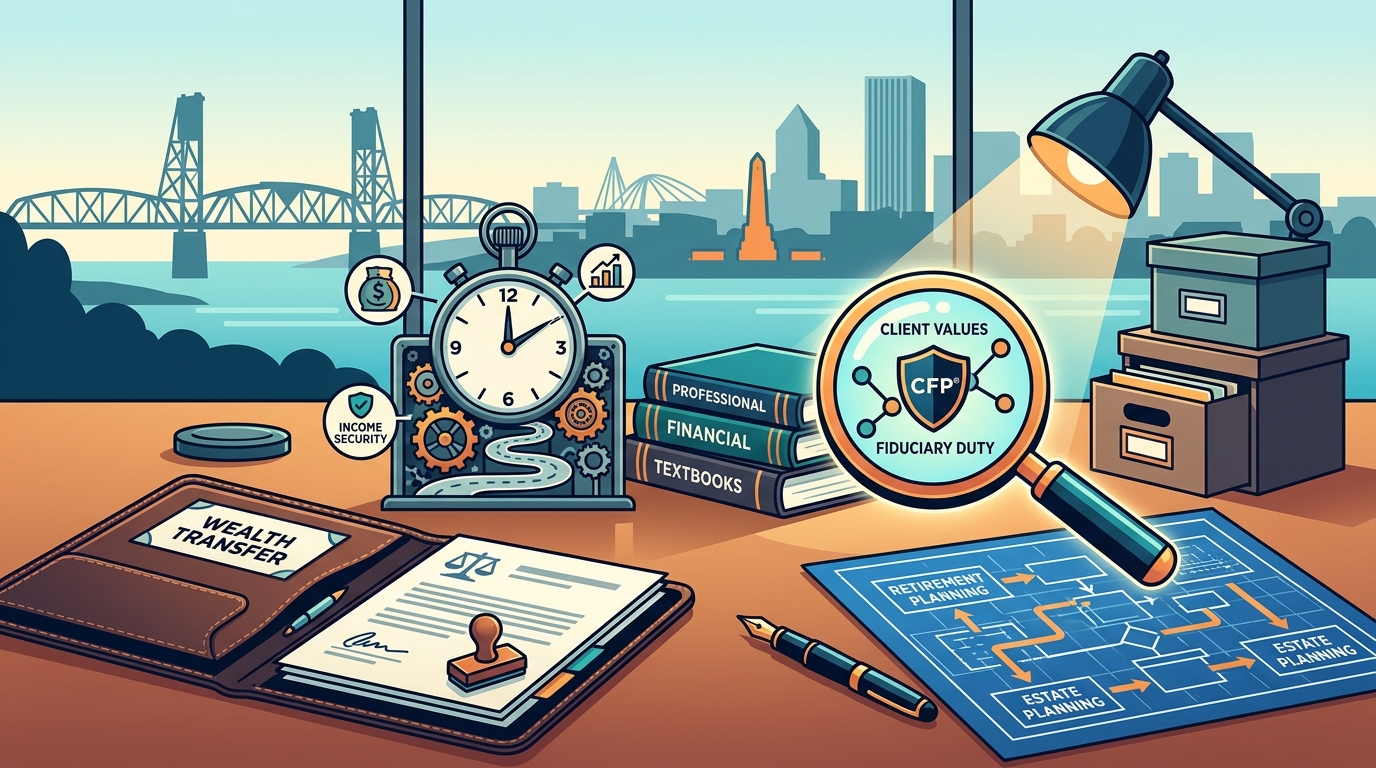
The Certified Financial Planner (CFP ) mark is a professional certification that signifies a high level of education, examination, experience, and ethics. It is one of the most recognized credentials in the financial planning industry. To earn the CFP mark, a professional must complete a rigorous curriculum, pass a challenging exam, and maintain continuing education requirements. This certification ensures that the advisor is trained in a holistic approach to financial planning, which includes retirement, estate, tax, and investment planning. For additional details, review the About.
Education and Examination
CFP candidates must complete a curriculum that covers the six areas of financial planning: investment planning, tax planning, retirement planning, protection planning, estate planning, and education funding. The exam tests the ability to apply this knowledge to complex, real-world scenarios. This ensures that the advisor is not just selling a product but is capable of designing a comprehensive plan.
Ethics and Fiduciary Commitment
CFP professionals are bound by a strict code of ethics that requires them to act in the best interest of their clients. This ethical framework is a key differentiator from other financial professionals who may operate under a suitability standard. When you hire a CFP professional, you are hiring someone who has committed to a higher standard of care and accountability.
Estate Planning Services
Wills and Trusts
A will is a legal document that outlines how your assets should be distributed after your death. A trust, on the other hand, is a legal arrangement that allows a third party to hold assets for the benefit of beneficiaries. Trusts can be used to avoid probate, provide for minor children, or manage assets for beneficiaries with special needs. Advisors work closely with estate attorneys to ensure that these documents are aligned with your financial goals.
Beneficiary Designations
Beneficiary designations are the instructions you provide on retirement accounts and life insurance policies that determine who receives the assets upon your death. These designations override the instructions in your will. It is critical to keep these designations up to date, especially after major life events such as marriage, divorce, or the birth of a child. Advisors regularly review these designations to ensure they reflect your current wishes.
Fiduciary Duty Standards
Best Interest vs. Suitability
The suitability standard requires that a recommendation be suitable for the client's needs, but it does not require that it be the best option available. The fiduciary standard, however, requires that the recommendation be in the client's best interest. This distinction is crucial. A fiduciary advisor cannot recommend a product that pays them a higher commission if a lower-cost option is better for the client. This alignment of incentives is what makes fiduciary advisors a safer choice for long-term planning.
Fee-Only vs. Fee-Based
Fee-only advisors are compensated solely by fees paid by the client. They do not receive commissions or other compensation from third parties. This structure eliminates conflicts of interest and ensures that the advisor's advice is unbiased. Fee-based advisors, on the other hand, may receive both fees and commissions. While some fee-based advisors are fiduciaries, the potential for conflicts of interest is higher. When looking for an advisor who handles both estate and retirement planning, a fee-only fiduciary is often the preferred choice.
Identifying Fiduciary Financial Advisors
Fiduciary financial advisors are professionals who are legally and ethically bound to act in the best interest of their clients. They are typically certified as CFP professionals or hold other credentials that require a fiduciary standard. To identify a true fiduciary, you should ask direct questions about their compensation structure and their legal obligations. A transparent advisor will clearly explain how they are paid and how they avoid conflicts of interest.
Questions to Ask
When interviewing potential advisors, ask the following questions: Are you a fiduciary at all times? How are you compensated? Do you receive commissions or other compensation from third parties? What is your process for avoiding conflicts of interest? These questions will help you determine if the advisor is truly acting in your best interest. A reputable fiduciary advisor will welcome these questions and provide clear, honest answers.
First Pacific Financial's Approach
First Pacific Financial is a fee-only, fiduciary advisory firm. Our team of CFP professionals is committed to providing unbiased advice that is in the best interest of our clients. We do not sell products or receive commissions. Our compensation is based solely on the value we provide to our clients. This structure ensures that our advice is free from conflicts of interest and is focused entirely on your financial goals.
Retirement Planning Execution
Asset Allocation and Risk Management
Asset allocation is the process of dividing your investment portfolio among different asset categories, such as stocks, bonds, and cash. The right asset allocation depends on your risk tolerance, time horizon, and financial goals. As you approach retirement, your asset allocation may shift to become more conservative to protect your capital. Advisors help you determine the right mix of assets and rebalance your portfolio as needed.
Monitoring and Rebalancing
Monitoring involves regularly reviewing your portfolio to ensure it is aligned with your goals. Rebalancing is the process of adjusting your asset allocation to maintain your target mix. Over time, the performance of different asset classes can cause your portfolio to drift from its target allocation. Rebalancing helps you stay on track and manage risk. Advisors perform this monitoring and rebalancing on your behalf, ensuring that your portfolio remains aligned with your retirement goals.
Estate Planning Integration
Estate planning integration is the process of aligning your estate plan with your overall financial plan. This ensures that your legal documents, beneficiary designations, and investment strategies are all working together to achieve your goals. A disconnected estate plan can lead to unintended consequences, such as higher taxes or delays in asset distribution. Advisors work with estate attorneys to ensure that all components of your plan are integrated and consistent.
Coordination with Legal Counsel
Advisors do not provide legal advice, but they work closely with estate attorneys to ensure that your financial plan is supported by appropriate legal documents. This collaboration is essential for a comprehensive estate plan. The advisor provides the financial data and analysis, while the attorney drafts the legal documents. This partnership ensures that your estate plan is both legally sound and financially efficient.
Long-Term Care and Medicaid
Long-term care is a significant expense that can deplete retirement savings. Estate planning includes strategies to protect assets from long-term care costs, such as the use of Medicaid Asset Protection Trusts. These strategies must be implemented well in advance of the need for care. Advisors help you evaluate your risk for long-term care and develop strategies to protect your assets while still qualifying for government benefits if needed.
Comparison of Advisor Types
| Advisor Type | Compensation | Standard of Care | Best For |
|---|---|---|---|
| Fee-Only Fiduciary | Client Fees Only | Fiduciary (Best Interest) | Comprehensive Planning, Estate & Retirement |
| Fee-Based | Fees and Commissions | Varies (Suitability or Fiduciary) | Product-Specific Needs |
| Commission-Only | Commissions | Suitability | Transaction-Based Needs |
Key Takeaways
- First Pacific Financial is a fee-only, fiduciary firm in Vancouver, WA, that integrates retirement and estate planning.
- The CFP certification ensures a high level of education, ethics, and holistic planning expertise.
- Fiduciary duty requires advisors to act in the client's best interest, avoiding conflicts of interest.
- Fee-only compensation structures eliminate product bias and align advisor incentives with client goals.
- Retirement planning requires a tax-managed withdrawal strategy to maximize lifetime income.
- Integration between financial and legal planning is essential for a seamless wealth transfer.
- Choosing a fiduciary advisor provides the highest level of protection and accountability for your financial future.
Frequently Asked Questions
What is the difference between a fiduciary and a suitability standard?
A fiduciary standard requires an advisor to act in the client's best interest, while a suitability standard only requires that a recommendation be suitable for the client's needs. The fiduciary standard is a higher level of care and protection for the client.
Does First Pacific Financial provide legal advice?
No, First Pacific Financial provides financial planning and advice. We work closely with estate attorneys to ensure that your financial plan is supported by appropriate legal documents, but we do not draft legal documents or provide legal advice.
How much does a fiduciary financial advisor cost?
Fee-only fiduciary advisors typically charge an asset-based fee, a flat fee, or an hourly rate. The cost depends on the complexity of your plan and the services you require. First Pacific Financial provides transparent fee structures that are based on the value we provide.
Can a financial advisor handle both retirement and estate planning?
Yes, many financial advisors, particularly those with the CFP certification, are trained in both retirement and estate planning. They work with estate attorneys to ensure that these two areas of planning are integrated and aligned with your overall goals.
What is the CFP certification?
The CFP certification is a professional credential that signifies a high level of education, examination, experience, and ethics in financial planning. It is one of the most recognized credentials in the industry and ensures a holistic approach to planning.
Why is fee-only compensation important?
Fee-only compensation eliminates conflicts of interest because the advisor is paid solely by the client. This ensures that the advisor's advice is unbiased and focused entirely on the client's best interest, rather than on selling products that generate commissions.
How often should I review my estate and retirement plan?
You should review your plan annually or after any major life event, such as marriage, divorce, birth of a child, or significant change in income or assets. Regular reviews ensure that your plan remains aligned with your current goals and circumstances.
Conclusion
Choosing the right financial advisor is one of the most important decisions you will make for your financial future. A fiduciary advisor who specializes in both retirement and estate planning can provide the comprehensive guidance you need to achieve your goals. First Pacific Financial is committed to providing fee-only, fiduciary advice that is in your best interest. Our team of CFP professionals in Vancouver, WA, is ready to help you navigate the complexities of retirement and estate planning. Contact First Pacific Financial to schedule a consultation and take the first step toward a secure financial future. Learn more: Fiduciary Financial Advisors Vancouver.