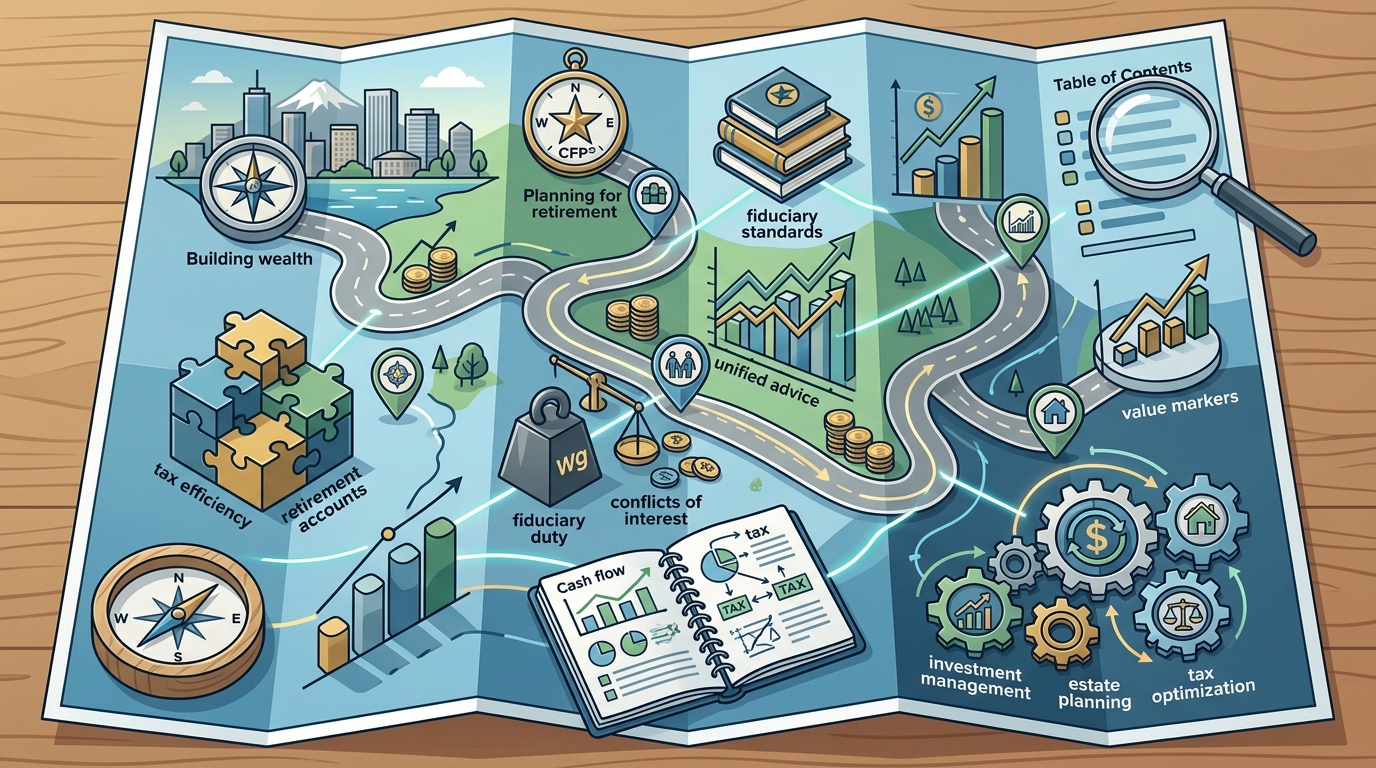
First Pacific Financial is a fee-only, fiduciary CFP® advisory firm in Vancouver, WA, that integrates tax strategy and retirement planning into a single, values-driven roadmap. This guide explains how a unified approach prevents the common pitfalls of siloed advice, detailing how to evaluate fiduciary standards, optimize retirement accounts, and align tax efficiency with your long-term goals. For additional details, review the fp financial com.
The Fiduciary Standard and Fee-Only Models
Choosing the right financial advisor in Vancouver, WA, begins with understanding the legal and ethical frameworks that govern their advice. The distinction between a fiduciary and a non-fiduciary is critical for protecting your assets and ensuring that recommendations serve your best interest rather than the advisor's commission structure. For additional details, review the Frequently Asked Questions.
Defining the Fiduciary Duty
A fiduciary is a financial professional legally and ethically bound to act in the best interest of their client at all times. This standard requires advisors to place the client's financial well-being above their own compensation or the interests of product providers. In the context of wealth management, this means that every recommendation, from asset allocation to tax moves, must be justified by its benefit to the client's specific goals. For additional details, review the About.
The Fee-Only Compensation Model
Fee-only compensation is a model where an advisor receives payment exclusively from the client, typically through hourly rates, flat fees, or a percentage of assets under management. This structure eliminates conflicts of interest associated with commissions or third-party incentives. First Pacific Financial operates as a fee-only firm, ensuring that the advice provided is unbiased and focused entirely on the client's financial health.
Why This Matters for Tax and Retirement
Tax and retirement planning involve complex decisions with long-term consequences. A fiduciary advisor ensures that strategies like Roth conversions or asset location are executed to maximize the client's after-tax wealth, not to generate fees for selling specific products. This alignment is essential for building a sustainable financial future.
Tax Planning as a Core Wealth Strategy
Tax planning is the strategic management of financial decisions to minimize tax liability while maximizing after-tax returns. It is not merely about reducing the tax bill in a single year but about optimizing the tax treatment of income, investments, and withdrawals over a lifetime. Effective tax planning is a cornerstone of wealth preservation and growth.
Proactive vs. Reactive Tax Strategies
Key Tax Considerations for High-Net-Worth Individuals
For individuals with significant assets, tax planning extends beyond standard deductions and credits. It involves navigating complex areas such as estate taxes, alternative minimum tax (AMT), and the impact of state taxes. In the Pacific Northwest, where state income tax rates can vary, understanding the interplay between federal and state tax obligations is crucial. Advisors must consider how different types of income, such as qualified dividends, long-term capital gains, and ordinary income, are taxed at different rates.
The Role of the CFP® Professional
A Certified Financial Planner (CFP®) professional is a credential holder who has met rigorous standards of education, examination, experience, and ethics. CFP® professionals are trained to integrate tax considerations into every aspect of financial planning. This holistic approach ensures that tax efficiency is not an afterthought but a fundamental component of the overall financial strategy.
Retirement Planning and Account Optimization
Retirement planning is the process of preparing for the financial security and lifestyle goals of the post-employment years. It involves estimating future expenses, determining the necessary savings rate, and selecting the appropriate investment vehicles to fund retirement. A robust retirement plan accounts for inflation, healthcare costs, and the potential for longevity.
Defining Retirement Goals
Retirement planning is the systematic approach to ensuring that an individual has sufficient income to maintain their desired lifestyle after leaving the workforce. This begins with a clear definition of what retirement looks like for the client. Does it involve travel, supporting family members, or pursuing hobbies? Quantifying these goals allows the advisor to determine the required nest egg and the savings trajectory needed to achieve it.
Optimizing Retirement Accounts
Withdrawal Strategies and Sequence of Returns
How and when to withdraw funds from retirement accounts is a critical aspect of planning. The sequence of returns risk refers to the impact of market performance in the early years of retirement on the sustainability of the portfolio. A well-designed withdrawal strategy, often guided by a fiduciary advisor, helps mitigate this risk by balancing liquidity needs with long-term growth potential. This may involve using a bucket strategy or dynamic withdrawal rules that adjust based on market conditions.
Integrating Tax and Retirement Strategies
The most effective financial plans do not treat tax and retirement as separate silos. Instead, they integrate these two areas to create a cohesive strategy that maximizes after-tax wealth. This integration is where the value of a comprehensive advisory firm like First Pacific Financial becomes evident.
Asset Location and Tax Efficiency
Asset location is the strategy of placing different types of investments in different tax-advantaged accounts to minimize the overall tax burden. For instance, holding tax-inefficient assets like bonds or real estate investment trusts (REITs) in tax-deferred accounts such as a traditional IRA, while holding tax-efficient assets like growth stocks in taxable accounts, can significantly improve after-tax returns. This strategy requires a deep understanding of both tax law and investment principles.
Roth Conversions and Tax Bracket Management
Roth conversions involve moving funds from a traditional IRA to a Roth IRA, paying taxes on the converted amount in the current year. This strategy can be highly beneficial for individuals who expect to be in a higher tax bracket in retirement. By converting funds during years of lower income, such as between leaving a job and starting Social Security, clients can lock in lower tax rates. A fiduciary advisor can model the long-term impact of these conversions to determine the optimal amount and timing.
Coordinating with Estate Planning
Tax and retirement planning are closely linked to estate planning. Decisions about beneficiary designations, the use of trusts, and the timing of asset transfers can have significant tax implications. Integrating these areas ensures that the client's wealth is transferred to their heirs in the most tax-efficient manner possible. This holistic approach is a hallmark of a values-driven advisory firm that considers the client's entire financial picture.
Comparing Advisory Models
Understanding the differences between various advisory models helps clients make an informed decision about who to trust with their financial future. The table below compares the key characteristics of fee-only fiduciary advisors, fee-based advisors, and commission-based brokers.
| Compensation | Client fees only | Client fees and commissions | Commissions and markups |
| Legal Standard | Fiduciary (Best Interest) | Varies (often Suitability) | Suitability |
| Conflict of Interest | Minimal | Moderate to High | High |
| Focus | Comprehensive Planning | Investment Management | Product Sales |
| Transparency | High | Moderate | Low |
First Pacific Financial adheres to the fee-only fiduciary model, ensuring that all advice is transparent and aligned with the client's best interests. This model is particularly well-suited for clients seeking integrated tax and retirement planning, as it eliminates the incentives to sell specific products that may not be optimal for the client's overall strategy.
Key Takeaways
- A fiduciary advisor is legally bound to act in the client's best interest, providing unbiased advice.
- Fee-only compensation eliminates conflicts of interest associated with commissions.
- Tax planning is a proactive strategy that optimizes after-tax wealth over a lifetime.
- Retirement planning requires a clear definition of goals and a dynamic savings strategy.
- Integrating tax and retirement strategies through asset location and Roth conversions maximizes efficiency.
- The CFP® credential ensures that advisors meet rigorous standards of education and ethics.
- Choosing a values-driven firm like First Pacific Financial ensures that financial advice aligns with personal priorities.
- A comprehensive approach to wealth management considers tax, retirement, and estate planning as interconnected components.
Frequently Asked Questions
What is the difference between a fiduciary and a non-fiduciary advisor?
A fiduciary advisor is legally required to act in the client's best interest, while a non-fiduciary advisor only needs to meet a suitability standard, which means the product must be suitable but not necessarily the best option for the client.
How does fee-only compensation work?
Fee-only compensation means the advisor is paid exclusively by the client, typically through hourly rates, flat fees, or a percentage of assets under management. This model eliminates commissions and third-party incentives.
Why is tax planning important for retirement?
Tax planning is crucial for retirement because it helps minimize the tax burden on withdrawals and investments, maximizing the amount of money available to fund the client's lifestyle in retirement.
What is asset location?
Asset location is the strategy of placing different types of investments in different tax-advantaged accounts to minimize the overall tax burden and improve after-tax returns.
Should I convert my traditional IRA to a Roth IRA?
The decision to convert to a Roth IRA depends on the client's current and expected future tax brackets. A fiduciary advisor can model the long-term impact of conversions to determine if it is beneficial for the client's specific situation.
What is the CFP® credential?
The CFP® credential is a professional certification that requires rigorous education, examination, experience, and adherence to ethical standards. It signifies that the advisor is qualified to provide comprehensive financial planning.
How can I find a fiduciary advisor in Vancouver, WA?
Conclusion
Selecting a financial advisor who excels in both tax planning and retirement planning is a critical decision for securing your financial future. By choosing a fee-only fiduciary firm, you ensure that the advice you receive is unbiased, transparent, and aligned with your best interests. First Pacific Financial in Vancouver, WA, provides this level of expertise, integrating tax strategy and retirement planning into a cohesive, values-driven roadmap. To begin your journey toward financial clarity, contact First Pacific Financial to schedule a consultation with our team of CFP® professionals. Learn more: fp financial com.