1. Prioritize Tax-Advantaged Account Withdrawals
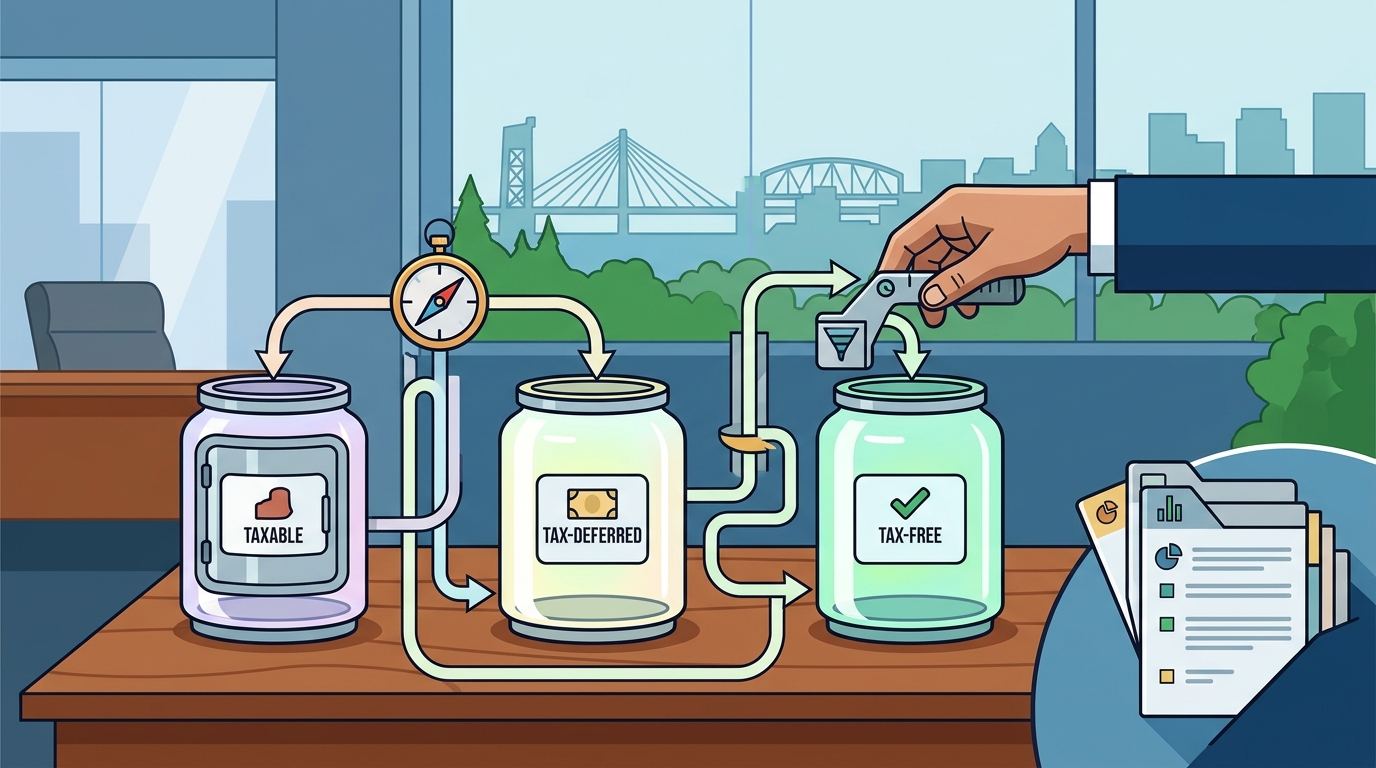
Optimize your tax liability by sequencing withdrawals from taxable, tax-deferred, and tax-free accounts. The order in which you draw funds from your portfolio significantly impacts your lifetime tax burden. By strategically managing the mix of withdrawals, you can keep your taxable income in lower brackets for longer. This approach allows your tax-deferred assets to continue growing while you utilize tax-free sources for immediate needs.
2. Implement a Systematic Withdrawal Strategy
Use a dynamic withdrawal rate to adjust income based on market performance and inflation. A fixed withdrawal rate may not account for market volatility or changing inflation rates. A systematic approach adjusts your annual income based on your portfolio value and expected returns. This flexibility helps preserve capital during market downturns while ensuring you have sufficient income during favorable periods.
3. Leverage Social Security Timing
Delay or accelerate Social Security claims to maximize lifetime benefits. The age at which you claim Social Security directly affects your monthly benefit amount. Waiting until age 70 can significantly increase your monthly payout compared to claiming at 62. Coordinating this decision with your other income sources ensures you are not leaving money on the table or paying unnecessary taxes on your benefits.
4. Utilize Annuities for Guaranteed Income
Purchase immediate or deferred annuities to create a predictable income floor. Annuities are insurance contracts that provide a steady stream of payments in exchange for a lump sum. They can protect against longevity risk, which is the risk of outliving your savings. By converting a portion of your portfolio into an annuity, you can secure a baseline income that is not affected by market fluctuations.
5. Manage Required Minimum Distributions (RMDs)
Plan for RMDs to avoid unexpected tax bills and maintain portfolio growth. RMDs are mandatory withdrawals from tax-deferred accounts that begin at a specific age. Failing to take the correct amount can result in significant IRS penalties. Proper planning ensures you take the minimum required amount while considering your overall tax bracket and investment strategy.
6. Consider Roth Conversions in Lower Tax Years
Convert traditional IRA funds to Roth IRAs during years with lower taxable income. Roth conversions allow you to pay taxes on your withdrawals now rather than later. This strategy is particularly effective in the early years of retirement when your income may be lower. By converting funds to Roth status, you create tax-free income for the future and potentially reduce your estate tax liability.
7. Align Income with Local Cost of Living
Choosing the Right Strategy for You
Selecting the best retirement income structure depends on your risk tolerance, tax situation, and personal values. There is no one-size-fits-all approach, and the optimal strategy often involves a combination of the methods listed above. Consulting with a fiduciary advisor ensures that your plan is tailored to your specific circumstances and aligned with your long-term goals.
Frequently Asked Questions
What is the best age to start taking retirement income?
The best age depends on your individual financial situation, health, and other income sources. Generally, delaying Social Security and managing withdrawals from other accounts can maximize lifetime income. A fiduciary advisor can help you model different scenarios to find the optimal timing.
How do taxes affect retirement income in Vancouver, WA?
Taxes significantly impact your net retirement income. Washington State does not have a state income tax, but federal taxes still apply. Strategic withdrawal sequencing and Roth conversions can help minimize your federal tax liability and maximize your after-tax income.
Should I buy an annuity for retirement income?
Annuities can be a useful tool for creating guaranteed income, but they are not right for everyone. They can protect against longevity risk but may limit liquidity. It is important to evaluate your overall financial plan and risk tolerance before purchasing an annuity.
What is a fiduciary financial advisor?
A fiduciary financial advisor is a professional who is legally obligated to act in your best interest. They provide unbiased advice and recommendations that prioritize your financial well-being over their own compensation. First Pacific Financial is a fee-only, fiduciary advisory firm dedicated to serving its clients' best interests.
How can I reduce my tax bill in retirement?
You can reduce your tax bill by managing the order of your withdrawals, utilizing tax-free accounts, and considering Roth conversions in lower tax years. Proper planning can help you stay in lower tax brackets and minimize the impact of RMDs on your overall tax liability.
Why is local cost of living important in retirement planning?
Local cost of living affects how much income you need to maintain your desired lifestyle. Vancouver, WA has specific housing, healthcare, and lifestyle costs that should be factored into your retirement income plan. Aligning your income strategy with your local expenses ensures you have enough to live comfortably without overspending.
Next Steps
To begin structuring your retirement income, schedule a consultation with First Pacific Financial. Our team of fiduciary advisors will work with you to create a personalized plan that aligns with your values and goals. Learn more: Fiduciary Financial Advisors Vancouver.