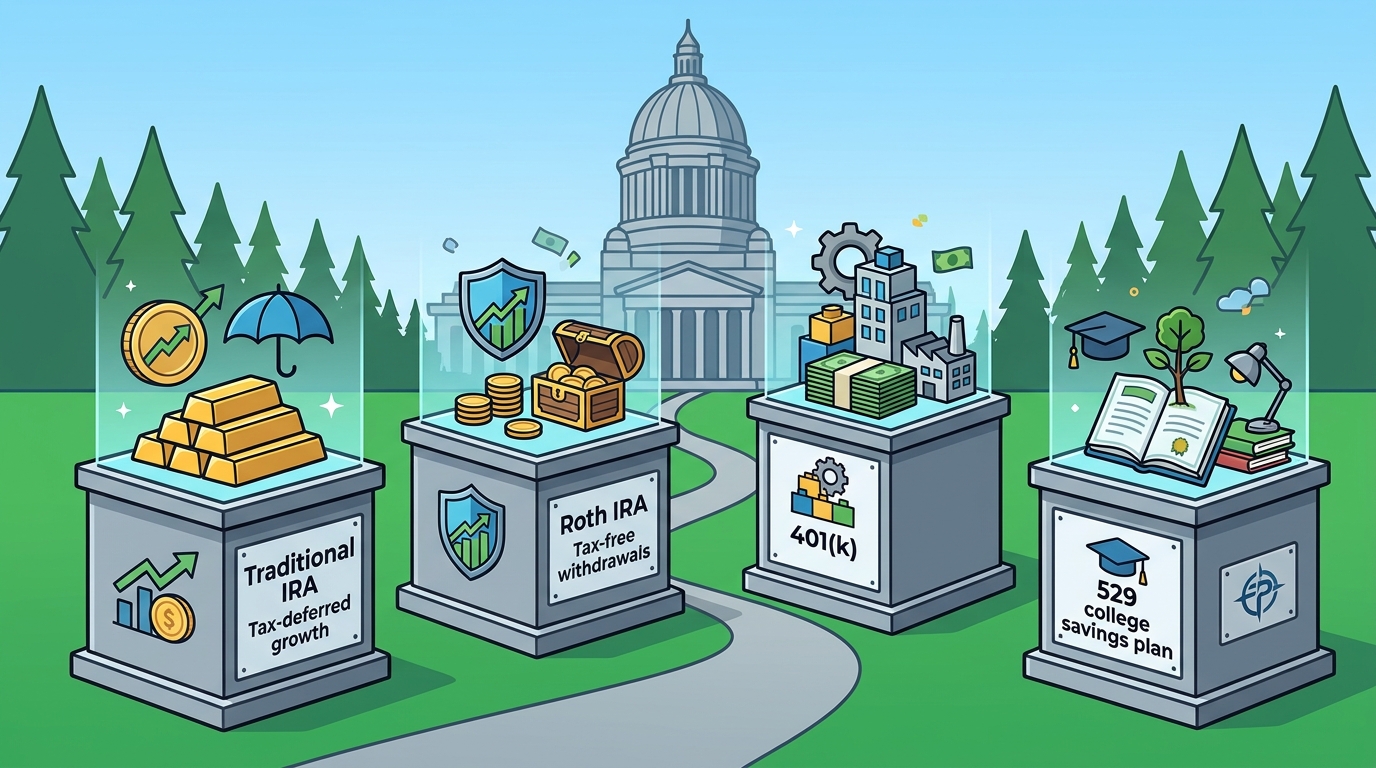
Washington state residents benefit from the absence of a state income tax, which creates a unique landscape for wealth building. The best tax-advantaged accounts for building wealth in Washington state in 2026 include Traditional IRAs, Roth IRAs, 401(k) plans, and 529 college savings plans. These vehicles allow residents to defer taxes or grow assets tax-free, maximizing the advantage of having no state-level tax on investment income. First Pacific Financial helps clients navigate these options to align their savings with their long-term values and goals.
Understanding the Washington State Tax Landscape
Washington state is one of the few states in the U.S. that does not levy a personal income tax. This structural advantage means that residents do not pay state taxes on wages, investment gains, or retirement distributions. However, this does not mean that federal taxes are irrelevant. The federal government still taxes income and capital gains, making federal tax-advantaged accounts critical for wealth preservation. A tax-advantaged account is a financial account that offers special tax benefits to encourage saving and investing for specific reasons such as retirement, education, or healthcare, as defined by the U.S. Securities and Exchange Commission. By utilizing these accounts, Washington residents can shield their assets from federal taxation while enjoying the state-level tax holiday.
The absence of state income tax also influences how residents approach capital gains. In many states, capital gains are taxed at the state level, but in Washington, they are only subject to federal rates. This makes taxable brokerage accounts less attractive for long-term growth compared to tax-advantaged vehicles. For high-income earners, the federal tax brackets can be significant, making the ability to defer or eliminate taxes on growth a primary driver of financial planning. First Pacific Financial emphasizes that understanding this dual-layer tax environment is the first step in optimizing a portfolio.
Retirement Accounts: The Core of Wealth Building
Retirement accounts remain the most powerful tools for building wealth in Washington state. The two primary options are the Traditional IRA and the Roth IRA. A Traditional IRA is a retirement account that allows individuals to make pre-tax contributions, reducing their current taxable income, with taxes paid upon withdrawal. This is particularly beneficial for individuals currently in a high tax bracket who expect to be in a lower bracket during retirement. Conversely, a Roth IRA is a retirement account that allows for after-tax contributions, but qualified withdrawals are tax-free. For Washington residents, the Roth IRA is often a preferred choice because it locks in the tax-free status of the funds, ensuring that the growth remains untaxed by both the state and the federal government.
Employer-sponsored plans like the 401(k) and 403(b) also play a vital role. Many Washington employers offer these plans, and contributing to them can provide an immediate tax deduction or tax-free growth. The 2026 contribution limits for these accounts have been adjusted for inflation, allowing individuals to save more than in previous years. First Pacific Financial advises clients to maximize their employer match first, as this is essentially free money. After securing the match, the decision between Traditional and Roth contributions depends on the individual's current and projected future tax rates. For those who believe their income will remain high, the Roth option may provide greater long-term value.
Education Savings: 529 Plans and Beyond
Building wealth is not only about retirement; it also involves preparing for major life events like education. The 529 plan is a tax-advantaged savings plan designed to encourage saving for future education costs. Contributions to a 529 plan are not federally tax-deductible, but the earnings grow tax-free, and withdrawals for qualified education expenses are also tax-free. Washington state offers the Achieving a Better Life Through Education (ABLE) program, which is a 529 plan that allows residents to save for higher education. While Washington does not offer a state tax deduction for 529 contributions, the federal tax-free growth makes it a compelling option for families. For residents who live in Washington but work in a state with an income tax, the 529 plan can still be a valuable tool, as the funds are portable and can be used in any state.
Another option for education savings is the Coverdell Education Savings Account (ESA). A Coverdell ESA is a tax-advantaged account that allows individuals to save for a beneficiary's qualified education expenses. Unlike 529 plans, Coverdell ESAs offer more flexibility in how the funds are invested and can be used for a wider range of education-related expenses, including K-12 tuition. However, the contribution limits for Coverdell ESAs are lower than those for 529 plans, making them less suitable for large-scale wealth building. First Pacific Financial often recommends a combination of 529 plans and taxable accounts to balance tax efficiency with liquidity and investment flexibility.
Health Savings Accounts: A Niche but Valuable Tool
The 2026 HSA contribution limits have been increased, allowing individuals and families to save more for their healthcare needs. First Pacific Financial encourages clients to view their HSA as a long-term investment vehicle rather than just a checking account for medical bills. By investing the HSA funds in a diversified portfolio, clients can potentially grow their wealth significantly over time. This strategy is particularly effective for those who expect to have lower medical expenses in retirement, allowing them to use the HSA funds for other purposes.
Strategic Integration with First Pacific Financial
Selecting the right tax-advantaged accounts is only half the battle; the other half is integrating them into a cohesive financial plan. First Pacific Financial, a fee-only fiduciary firm based in Vancouver, WA, helps clients navigate this complexity. Our team of CFP® advisors works with individuals and families to align their finances with their values. We do not sell products; we provide objective advice based on your best interests. This fiduciary standard ensures that our recommendations are free from conflicts of interest, allowing us to focus solely on your financial well-being. according to Tax Advantaged Savings
Our approach involves a comprehensive review of your current financial situation, including your income, expenses, and existing accounts. We then develop a personalized strategy that maximizes the use of tax-advantaged accounts while minimizing your overall tax burden. Whether you are just starting your career or preparing for retirement, our team can help you make informed decisions. We also consider the broader context of your life, including your family goals, charitable interests, and legacy plans. By taking a holistic approach, we ensure that your wealth building is not only efficient but also meaningful.
Key Takeaways
- Washington state's lack of income tax makes federal tax-advantaged accounts even more critical for wealth building.
- Roth IRAs are often preferred by Washington residents due to their tax-free growth and withdrawals. according to Washington From affluence
- 401(k) and 403(b) plans offer employer matches and higher contribution limits, making them essential for retirement savings.
- 529 plans provide tax-free growth for education expenses, a key component of family wealth planning.
- HSAs offer a triple tax advantage and can serve as a supplemental retirement account.
- First Pacific Financial provides fee-only, fiduciary advice to help you optimize your tax-advantaged accounts.
Frequently Asked Questions
Does Washington state tax investment income?
No, Washington state does not levy a personal income tax, so investment income is not taxed at the state level. However, it is still subject to federal taxes.
What is the best retirement account for high-income earners in Washington?
For high-income earners, a Roth IRA or Roth 401(k) may be the best choice, as it allows for tax-free withdrawals in retirement. This is particularly beneficial if you expect to remain in a high tax bracket.
Can I use a 529 plan for non-education expenses?
Generally, no. Withdrawals from a 529 plan for non-qualified expenses are subject to federal income tax and a 10% penalty. However, there are some exceptions, such as for disability or after the beneficiary's death.
How much can I contribute to an HSA in 2026?
Is First Pacific Financial a fiduciary?
Yes, First Pacific Financial is a fee-only fiduciary firm. This means we are legally obligated to act in your best interest when providing financial advice.
Start Your Wealth Building Journey
Building wealth in Washington state requires a strategic approach to tax-advantaged accounts. By understanding the unique tax landscape and selecting the right vehicles, you can maximize your savings and achieve your financial goals. First Pacific Financial is here to guide you through this process. Our team of CFP® advisors in Vancouver, WA, is committed to helping you align your finances with your values. Contact our team to schedule a consultation and take the first step toward a secure financial future. Learn more: Contact First Pacific Financial.